這類在 NFT 發展初期,出現的各種原生消費行為,與其說是購買單一數位藝術品,這些行為更像是買了這個社群的會員資格,可說是數位身份的象徵。當人人都把 Twitter 上的個人頭像,換成自己擁有的 Bored Ape 時,另一種數位身份 (Digital Identity) 的認同與價值也就此展開。而在數位當道的時代,數位身份比現實世界的身份地位來得更重要。如同 Hashmask 在自己的 Blog 寫道:
Sometimes I feel that our digital sense of identity has already surpassed our physical sense of identity in terms of importance. This holds true, particularly among younger generations. Nowadays, having an Instagram-worthy photo of a moment seems to be more important than the moment itself. And the trend will only accelerate, not go back. In the near future, our identity will most likely be fully digital. Who you are online will be more important than who you are at home and in the physical world.
David is an Associate mainly focused on investments. He previously lived in the US, but was drawn to the Greater Southeast Asia region by the growth opportunities and the wonderful people here. He spent the first five years of his career as a consultant at IBM, where he became intimately familiar with the enterprise software and services needs of Fortune 500 companies. Later, he focused on building predictive models and solving optimization problems for large companies, and gained an appreciation for the role of data and algorithms in our lives. He joined AppWorks in 2020 after receiving his MBA from Columbia Business School, and also has a B.S. in Mathematics from the Ohio State University. In his free time, he tries to stay active and is always looking for opportunities to hike or trek, often seeking the trail less traveled.
Hiring is a tricky thing no matter who you are and what the role is. But it’s doubly hard when you’re a startup founder and you’re making a key hiring decision in a new market you’re expanding to — you can’t afford to make any personnel mistakes this early on, especially when runway is limited and potential investors are gauging your execution on a promising new source of growth. And with advances in technology and globalization, the opportunity to enter another market has never been available so early, magnifying the importance of getting things right as a growing startup.
However, there are a few pitfalls that we as leaders and organizations succumb to at times, which can disproportionately impact hiring decisions in new markets. It’s good for leaders to be aware of these early on, well before you are ready to make such a hire, as it could take a bit of marinating to gain self-awareness. Here’s how people often go down the path of making the wrong hire:
Humans hate uncertainty… You’re expanding into a new market — a market that you’ve perhaps visited many times, whose people you’ve worked with and partnered with in the past, and on which you have done plenty of research. But let’s face it, if we’re being honest, when it comes to truly understanding the market, we can’t hold a candle to a native. And that’s totally okay! We can assess the uncertainty of the market, think of all the ways we might be wrong, all the ways we might fail, and all the ways we could hire the wrong people, and come up with a course of action which maximizes our expected return. Right?
You’re expanding into a new market — a market that you’ve perhaps visited many times, whose people you’ve worked with and partnered with in the past, and on which you have done plenty of research. But let’s face it, if we’re being honest, when it comes to truly understanding the market, we can’t hold a candle to a native. And that’s totally okay! We can assess the uncertainty of the market, think of all the ways we might be wrong, all the ways we might fail, and all the ways we could hire the wrong people, and come up with a course of action which maximizes our expected return. Right?
Unfortunately, that’s just not the way we are wired. Humans hate uncertainty. A 2016 study found that our stress levels were directly correlated to the uncertainty of the outcome, rather than the outcome itself. Not knowing how we’ll do on an exam is more stressful than being certain we’re going to fail. Receiving a call from your boss out of the blue is more stressful than knowing that she’s calling to fire you. And not knowing whether or not your startup will live is always more stressful than knowing it’s the end of the road.
So as humans, our instinct is to minimize this stress by suppressing the uncertainty. Despite the fact that external information is always incomplete and there are many types of uncertainties we have to deal with around hiring for a new market, in our mind we make things easy. We need to make ourselves feel in control. The kicker is that the same study found that our performance level increases with uncertainty. Feeling uncertain actually brings the best out of us, which makes quashing the uncertainty even worse.
…So we often latch on to our ownorganizational ideologies. Everyone has their own ideology based on what we have experienced in life. And when we are faced with key decisions to make, our ideology is what determines our decision. In the uncertainty of hiring for a new market, we suppress the stressful unknowns and default to something—anything to reduce the stress and give us some sense of control. So we default to our organizational ideology — it’s clean, easy, and certain. We hire the smartest person. And the smartest person, as we all know, is the one who most agrees with you — the one who conforms to your ideology the most.
Ideologies come to dominate organizations. And why wouldn’t you hire the person who fits the most into your ideology? Everyone successful at the company is like that. That is because of the systematic entrenchment of ideologies in organizations — through mentoring, feedback given to employees and through the interview process. People who don’t agree with the ideology don’t get in the door, and those who do get in the door are constantly pushed to conform even more. At some point you can’t even imagine working with someone who doesn’t share the same general views. Why wouldn’t you hire the person who agrees with your ideology? After all, the company has been successful and the ideology has worked so far. With everyone on the same page, it decreases the need for bureaucratic control and increases efficiency. There’s just one problem.
The organizational ideology doesn’t always transfer to the new market. We don’t actually understand the local market that well. We don’t fully understand how it’s different from our home market, and that our ideology might not be 100% the best fit for our new market. As you’re interviewing candidates for key hires in the new market, they may express views about which users to target, how to market the product, and how to build the organization on the ground. Chances are, if the person is a native and the market is different from your home market, you will have some disagreements. This is normal and a product of you being an outsider and living in your ideology, so you should think twice before dismissing such a candidate as you would if you were hiring for your home market.
Joel Leong, founder of ShopBack (AW#13), APAC’s leading cashback rewards platform, now in active nine countries across the region, has often spoken to us about not just hiring a local person to lead the new market, but fully empowering them and giving them the leeway and resources to execute the plan that they have developed, as if they were a founder themself. Joel often moves to the new country himself for several months at the beginning of each market entry to fully grasp what’s happening on the ground, but always passes on the reins to the country manager after setting up the local team.
We reach for control over local creative units. What’s even more dangerous is that we tend to feel most strongly about creative units like marketing and local product design. Many founders and organizational leaders are well-traveled global citizens who may have even studied and worked abroad. We may overestimate how well we actually understand the customer and how they respond to the product or the marketing. When local managers are telling you something that seems totally unintuitive given what you know about something subjective or creative, our first reaction will be to resist. This is in contrast to non-creative units like finance, IT, or production — boring stuff where local requests are usually approved without a second thought. Of course, the success of entering a new market often hinges on the creative aspects, so leaders should be mindful when hiring or evaluating local resources here.
CK Cheng, founder of AsiaYo (AW#12), the Series B travel booking platform which has raised $10 million to-date, shared a few experiences with me on this topic. At the outset of market expansion, AsiaYo used a centralized decision-making structure. “I made the decisions whenever I had a strong opinion, and I would take responsibility for them,” he says.
But later, as they expanded deeper into Japan and Korea and now Southeast Asia, they shifted to a decentralized structure covering their large geographical footprint. Why? “I realized my hit rate was so low [making the correct decisions]” he laughs. “Now, it doesn’t matter if I feel strongly about something or not – I’m not the person on the ground. So I spend more time making sure that the decisionmaker has a good decision-making framework, and is connected to the right stakeholders in the organization, so that they don’t need to consult me.”
CK describes his current hiring approach in new markets as “trust over capability” – placing more emphasis on trusting the candidate over his own subjective evaluation of their capability. To increase this trust, he stresses finding people recommended within his close personal network – both his Japan and Korea country managers were second-degree connections. By hiring based on trust and track record, he doesn’t need to worry about being on the exact same page in terms of strategy and approach.
So what can we do?
I think the first step is just awareness — being aware that all people have certain tendencies that are ingrained in our psychology. And that sometimes it works for us, but other times we need to take a step back and be very conscious of our blind spots, such as when we enter a new market, whether that’s geographic or otherwise. This is not as simple as it sounds when you are a manager or running a company; making a wrong decision in a new market is a scary thought and can lead to major consequences. It is easy to acknowledge that everyone has blind spots, but only when one understands the root of our own personal management psychology can we truly make an informed, unbiased decision.
When you’re making the hire, you might consider giving a long look to that candidate who firmly disagrees with you on the approach but has a proven track record of success in the new market. This way, you’re conscious of your own pitfalls and can actually use it to your advantage, by finding someone who disagrees with you in certain respects. And you can have confidence and trust in their execution given their prior record. Feel and embrace the discomfort that will surely come with this decision which stems from natural human tendencies. Let go, trust, and empower. This takes tremendous mental discipline but could be a practical way to make better hiring decisions.
【We welcome all AI, Blockchain, NFT, or Southeast Asia founders to join AppWorks Accelerator】
Sophie is an Associate in the investment team. Before joining AppWorks in 2020, Sophie had 10 years of experience covering public equities. She was part of the portfolio management team at Neuberger Berman, focusing on emerging market opportunities. Prior to that she served as a research analyst at Credit Suisse, JPMorgan, and London-based Autonomous Research. Sophie holds a Master of Finance with distinction from Warwick Business School and BS Finance from National Taiwan University. Her passion and expertise, however, extend far beyond just researching companies and industries. She is also an author of two published poetry books and holds a keen interest in human psychology and human behavior.
Whilst founders and early investors often regard an initial
public offering (IPO) as an end goal, public market investors rather see it as the company’s first
debut, akin to the NBA draft. With that said,
there are some key qualities that the capital
market looks for in a public company. In fact, there is already a standard of
what is regarded as a ‘good IPO.’ I believe by understanding this, mid-to-late
stage founder-CEOs can design a more
structured roadmap for going public, or even rethink whether
an IPO is actually the best option for their company. This piece of article is more written for growth
stage founder-CEOs. However, if you’re an
early-stage founder, I believe this article can also shed some light on what is ultimately valued the most
in the sometimes arcane process of filing for an IPO.
Trust is what helps
companies earn long-term loves in the public market. It’s a playing field with big guys that have already proved their sustainability, building layers upon layers of trust as
each quarter passes. Trust is cultivated not only through data (a result of management and
operation), but also through market reaction. This means, executing a good or even strong IPO is indeed very important because
the trust is then solidified from day one.
Three qualities: Growth, Size, and Momentum
From my 10 years of experience in both brokers and asset
management firms, I see growth, size, and
momentum the three qualities that
overwhelmingly dictate the success of an IPO. Usually
a banker would prepare a scorecard, rating a handful of factors that
advise the parameters of a public offering. But, these three in particular have
an outsized impact on a company’s debut, and understanding
their underlying mechanics can help founders
become more informed before they enter the negotiating room and differentiate true advice from sweet words. I will also introduce
a few unfortunate case studies to help illustrate the importance of these factors.
Growth
Growth, like in any fundraising process, is the most important factor. In the public market, growth expectations are not as high as in private, early-stage startups where 100% month-over-month is the norm. However, a 3-year compound annual growth rate (CAGR) of 50-60% is still an ideal benchmark to strive towards, at least for a technology company. Consequently, timing of an IPO is a key consideration for startups; list while there are still strong growth prospects, otherwise poor market feedback is all but certain.
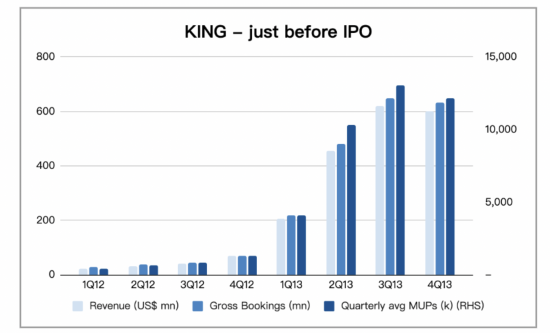
Candy Crush Saga, a staple among every grandma’s home screen, had gone through such pain. Its Irish parent company, King Digital Entertainment (delisted in 2016), first filed for an IPO in September 2013. Soon in December 2013, news about King’s consideration of delaying the IPO due to market concerns about the sustainable growth of the company had spread. Back then, Candy Crush Saga accounted for over 75% of King’s gross bookings and it has already reached 500 million downloads, topping the charts of the iTunes store. From the IPO filing, monthly unique players (MUPs) had already declined in the latest quarter by 6.5% , whilst gross bookings and revenues dropped 2-3%. This implied a negative signal for the growth expectations post IPO. The resulting impact on King’s stock price was evident, down 16% on the day of the IPO, with its valuation dropping US$ 2 billion (from US$ 7 billion) in the span of two months. Moreover, the follow-up financial reports confirmed the market’s concerns; King delivered a mere 20% in revenue growth in 2014, and subsequently declined 25% in 2015.
Chart: KING already showed a decelerating trend of MUPs and Gross Bookings in the last reported quarter (4th quarter in 2013) before IPO.
Size
Size is a very important factor, but often overlooked by many startup
founders; although, it may matter less if the growth rate is significant, say 80-100%
year over year. Size encompasses both a company’s market cap and daily trading value and collectively determines the number of investors that can potentially
participate. In Asia, the most ideal professional fund size is at least US$ 1-3
billion, which means an average position would be minimum US$ 20 million. This
implies two things: (1) since most funds are
not allowed to own more than 10% of the company, there’s an implied minimum market cap of US$
200 million; and (2) even if a fund is willing to trade for 60 days (three
months of working days) to buy enough shares,
it means the daily trading value needs to be US$ 1.6 million at least (assuming
a fund would not trade more than 20% of the amount to avoid affecting the
price). However, the math here represents the bare minimum case. Most investors consider US$ 500-1,000 million as the bottom threshold for market cap, with anything below yielding
very little appetite.
Many startups in Asia might face issues here. In Taiwan, it is a very common experience.
For example, we have Kuo Brothers (8477
Taiwan), one of the main e-commerce players that was listed at a valuation of
only US$ 30 million. This already implied a potential daily liquidity lower
than US$ 1 million, greatly limiting the size of the potential investor
pool. I was fortunate enough to chat with the chairman of Kuo Brothers Jerry
Kuo and get his thoughts on this matter: “We certainly recognise the limit from
our size, which actually leads to Kuo Brothers being greatly undervalued.
However, coming to the public market still has its beauty, especially in talent
recruiting and business expansion, at least for Kuo Brothers at the current
stage. I believe in time the market will recognise our value as we grab more
shares from this highly potential market in Taiwan.”
Despite many Southeast Asian stock markets sharing similar features as Taiwan’s, founders in this region have long recognized the necessity
to expand and reach a certain scale before even
thinking about filing for a public offering. Sea
Group’s 2017 IPO on the NYSE paved the way for
Southeast Asian startups. It was the first unicorn from the region that went public at a valuation of over US$ 4 billion. Many other
unicorn startups in excess of that size including Grab, Traveloka, and Gojek
are now on deck.
Momentum
Momentum is the last but
no less critical factor for a successful IPO. When I
say momentum, I mean the market reaction in the first couple of days or months preceding
a company’s first day of trading. Some may regard
momentum as a function of trading or
expectation management. I would define it as a
reflection of a founder’s ability to deliver on their promise to the market. Momentum is generated only
if a company achieves, if not exceeds its forward-looking guidance. It is about
execution. If there are any technical matters to take into
consideration, at most I would suggest avoiding setting your listing window
during major political or economic events such as elections or Fed meetings.
I would categorize momentum into three stages. These stages
all matter, but it’s better if a
company builds a strong momentum throughout, or at least exhibits a gradually recovering trend.
Stage
1: The IPO day – I would recommend that
a company must never underestimate IPO day. It very often sets the tone of the
market reaction. It is a direct reflection of the market’s appetite or view of
the IPO pricing, and future growth potential. When deciding the IPO valuation, higher doesn’t necessarily always mean better; a valuation on the high
end could lead to inflated expectations and therefore a higher probability of
price correction on IPO day.
Stage
2: Before the first reporting –
Investors tend to build some buffer in their model. They tend to apply some, if not a major discount to the
guidance outlined in a company’s IPO prospectus. That
is why expectations are rather mixed and vulnerable before the first reporting.
Do not do anything that leads to further doubt. Again, it is about execution. A
company should deliver what it has promised, signalling that the
business is on track and in good hands. Any mistake (or misfortune) at this stage
could instantly break investor trust, requiring
an extensive amount of time and effort to rebuild it.
Stage
3: First reporting day – A company
should deliver a good set of results that are in line with the guidance provided during the IPO process.
The market reaction on the first reporting day will anchor a basic view on the
company. If the reaction is strong, the company would have secured a
solid level of trust among investors. On the other hand, a bad reaction would take
extra effort and time to rebuild the company’s positioning in investors’ minds.
Snap’s IPO in 2017 is a great example here. Although Snap’s
share price surged 44% on the first day of trading, the stock price soon lost
momentum. Major reasons were related to the uncertainty of the IPO valuation,
which was at 62x P/S ratio vs. Twitter’s 4x and Facebook’s 13x back
then. Stock price fell 50% from the peak before the first reporting in the second quarter of
2017. However, the results made the situation worse. New installs of Snap dropped 21% year over year,
comparatively worse than Instagram’s 8% year-over-year increase in the
same period. Revenues and user growth also undershot, eliciting deep
disappointment among investors and sending the price of its stock even lower. After this, Snap hovered at a low-price range for two
years until they managed a comeback in 2019.
Focus on your flywheel
Given the qualities discussed, I hope you now have a better idea of what exactly it means to be IPO-ready. My final piece of advice echoes popular sentiment among the most common early-stage pitfalls to avoid—premature scaling. Do not prematurely go into an IPO for the sole purpose of competing against the big guys. We all agree that going IPO has its merits: It offers an exit for your early investors, and lets veteran employees realise the value of their ESOP and efforts. In the meantime, the public market is indeed an effective and open place for (friendly) funding. However one should not ignore the fact that public market investors are not like the VCs and angels who spend years watching your company grow. Every inch of your ambition, vision, and execution are now under the eye of public scrutiny, where investor reactions tend to be immediate and widely irrational. So irrational, in fact, that an entirely new field of study has emerged called behavioral finance, where a handful of psychologists and economists have already been awarded Nobel Prizes. When expectations go sour, both valuation and liquidity (trading value) drain even faster. This vicious cycle can significantly impede the value and momentum of your business, taking years to build up again.
Therefore, I would highly recommend growth stage founders put a proper plan in place when considering an IPO. Make sure you have good growth, good size, and good execution and hence can deliver good initial momentum. Only then will you be in a position to reap the full benefits of the public market.
【We welcome all AI, Blockchain, NFT, or Southeast Asia founders to join AppWorks Accelerator】
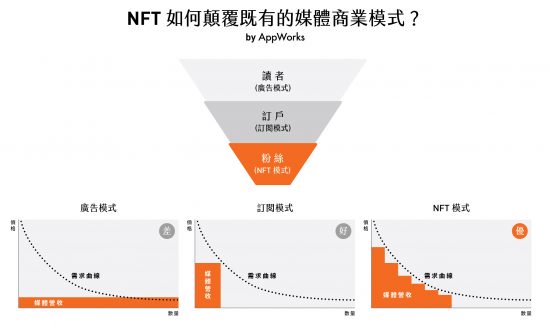
衡量每個 NFT 的價值,技術並非主要考量,最重要的關鍵,在於發行者的 IP 或是 NFT 內所涵蓋的內容。好的內容來自有特殊的歷史意義、創新的表達方式、獨到的詮釋觀點與角度⋯⋯等各種面向,也因此,媒體用心製作的好內容,在 NFT 的模式下,將有更多元、更有效率的內容變現機會。
《連線》(Wired) 雜誌創辦人、科技趨勢思想家 Kevin Kelly 在 2008 年的經典文章「1,000 位鐵粉」(1,000 True Fans) 就預言:「成功的創作者,你不需要數百萬位客戶,你只需要 1,000 位鐵粉 (True Fans),這些鐵粉,會購買任何你創造的商品。」
對媒體來說,NFT 模式則將 Kevin Kelly 的預言更進一步實現,因為鐵粉有更方便、更實質的支持方式。以我個人為例,從小就愛閱讀雜誌、大學編校刊,從第一份工作開始投入雜誌與媒體工作 18 年,至今仍收藏許多雜誌,例如 911 事件、Michael Jackson 過世、Steve Jobs 過世、歐巴馬首度當選美國總統、Facebook 用戶突破 10 億人⋯⋯等重要歷史事件,我都會選擇我最信任的雜誌品牌,購買能提供我最權威、最具歷史意義觀點的當期雜誌來收藏,甚至會購買收藏特殊期數的復刻版;在雜誌工作時,也經常會有企業、受訪者或是教學單位,希望授權報導的文字內容、照片、資訊圖表 (通常收不到什麼錢)。在 NFT 模式下,這些行為都變得更有意義與價值,媒體有更具體的變現與獲利方式,收藏者手中具有歷史意義、特殊價值的媒體內容,也有了更客觀與便利的鑑價和割愛交易方式。
Jack is an Analyst covering AppWorks Accelerator. Before joining the team, he was a co-founder and early team member at two InsurTech startups, where he developed a passion in user experience and product development. Previous to his startup journey he worked as a commercial property underwriter at Chubb Insurance in New Zealand. Jack graduated with a Bachelor of Music from Waikato University where he studied classical piano. He loves to cook, read and is a practicing stoic.
Hi, I’m Jack, I joined AppWorks as an Analyst in April 2019, not long after I burnt through two startups, one I co-founded in 2017 and the other as a founding team member. My experience taught me that building a successful company is extremely difficult, and if I wanted to improve my odds, I needed to learn from people who have successfully built them.
Now at AppWorks, I get to work alongside 1,300 founders of all stages amongst a variety of startups, 395 active ones to be exact, across the most exciting region that is Greater Southeast Asia, giving me truly a grand scope of founders to learn from.
This year, the coronavirus disrupted the normal world order, taking millions of lives in the process and slowing down economies all around the world. Amongst the chaos, startups from all stages were affected. Besides the select few that prevailed, most startups either saw stagnant growth, or worst, shut down their business.
On my journey to become a better founder myself, behind this very unfortunate event was a learning opportunity of a lifetime. This is why I set out to write this piece, to document my learnings and improve my understanding. I got to see just how startups that overcome the pandemic reacted differently to those that didn’t.
Amongst our network of founders, I had the chance to closely observe Ming Ming Chen, the founder and CEO of KKday – a travel platform that provides local experiences and tours across Asia. I got to witness first hand how he coped with drastic changes that affected his business, how he made quality decisions that pushed KKday to prevail, and how he quickly mobilized the entire company to effectively weather the storm.
I believe the key lessons distilled here are applicable to early-stage founders all the way up to founders heading into series B, especially for those that want to learn how to lead a team through uncertainties. The COVID-19 pandemic is a once-in-a-generation crisis, pushing founders to the test in every single aspect possible, so the lessons observed here should be great additions to your arsenal.
First, plan for the worst to conquer yourself
Back in January when the pandemic first broke out, I hopped on a call with Ming Ming to check in on KKday’s pulse. I remember distinctly that he was very calm and collected. It was hard to tell from his demeanor that 90% of travel in this region was wiped out almost over night.
I asked him what’s going through his head. Ming Ming mentioned that in his 20+ years of entrepreneurship, a key principle he practiced was to always plan for the worst.
By always planning for the worst, KKday has been extremely disciplined in managing their cash flow and balance sheet. The key principle is to not sink short-term assets into long-term investments, optimizing for cash flow flexibility in return.
This played a major role in neutralizing the initial shock of the outbreak, allowing KKday to protect their brand and refund customers fully, despite a significant drop in revenue.
The other benefit of planning for the worst is better managed expectations. When bad situations don’t turn out as bad as you had anticipated, then your own morale and energy are left unperturbed.
This side effect may seem negligible at first, but being the captain of the ship that’s lost at sea, the crew’s attitude is an extension of it’s captain. Displaying the slightest frustration and anger does not instill confidence in your team, but only serves to discourage them. What seemed like a minuscule change in perspective can actually impact the entire company.
By simply planning for the worst situation possible, Ming Ming and KKday were able to soften the initial blow of the pandemic. But as the travel industry came to a near freeze, how can a founder turn around their startup’s fate from barely managing survival to proactively creating opportunity?
A decision framework against uncertainty
Having led 2 companies to IPO before starting KKday, Ming Ming draws from a wealth of knowledge and experience to overcome the pandemic. He explains that the result of any decision is amplified during troubled times, either directly adding more uncertainty to your team or reducing it.
Furthermore, the result also impacts the decision maker’s future credits to lead their team. Thus, increasing the decision quality across the company was a key lever to pushing KKday forward.
Ming Ming distilled his decision framework into for steps ”見-識-謀-斷” which can be translated to “seek-digest-strategize-decide”. Every decision made within KKday goes through this rigorous process.
The first step is to “seek” information and data that’d accurately represent the reality of the decision. The second step is to “digest” the information and to understand the scope and the stakes. The third step is to “strategize”, plan and test the hypothesis of your decision; it is important to stress test your thesis and evaluate whether or not it adequately stands up to reality by inviting other stakeholders into the discussion to either validate or invalidate your understanding.
The last step is to “decide”. The founder or the leader of the team needs to make the decision alone, as they need to carry the responsibility of the result. They need to decide on the tradeoffs of making the decision, and whether or not to proceed or revisit the preceding steps.
Throughout 2020, KKday has transitioned from selling tours for foreigners traveling in a new country to weekend getaways and other domestic excursions for people living in Taiwan, while also branching into products that extend far beyond their typical offering including protective masks and packets of mala hot pot.
In the process of venturing into the unknown, Ming Ming and his team carefully used this framework to test their hypothesis, efficiently and effectively pushing forward their progress without losing precious resources and energy.
And as the year draws to a close, we are seeing all of these initiatives not only making up for the missing revenue, but also enabling KKday to strengthen its brand and build goodwill among its customer base, while acquiring a slew of new users in the process.
But making better decisions is only part of the equation, what truly pushed KKday above the line was their execution upon these decisions. So just how did KKday, a company with hundreds of employees, with operations spanning across 6 countries adapt to the new normal so swiftly?
Using organization structure to drive your strategy
Much like a sports team that changes their lineup according to their game plan and the opposing team, a founder needs to structure their organization and teams relative to the environment and strategy, to maximize the organization’s output.
Once Ming Ming and his team decided to introduce new products and focus on domestic travel, the way the organization was previously structured needed to be reshaped, as it no longer yielded optimal efficiency in promoting the new strategy.
Rather than having the Taiwan HQ team approve all products for travelers on their platform, KKday adapted to procuring products locally, authorizing local teams to source products for their own markets allowing them to move much faster than before.
The teams also overhauled their KPIs to focus on improving new product sales and domestic travel sales. These new KPIs became the guidelines and instructions that empowered the new teams to directly facilitate the change in strategy, enabling the company to quickly transition from serving outbound travelers to domestic travelers.
COVID-19 hit different countries with varying severity, creating non-linear recovery across all of KKday’s active markets. The organizational restructuring served as an effective way for local teams to rapidly respond to local conditions as needed, helping the travel company to pull off an incredibly successful year by all standard measures—no doubt exemplified by the US$ 75 million Series C they recently raised in the midst of a pandemic.
There is much more to learn
By always planning for the worst, Ming Ming was able to soften the initial impact for the pandemic, and by improving the decision quality across the board, KKday was able to create opportunities even when the odds were stacked against them. Most importantly, by efficiently managing the organization, KKday was able to execute quickly upon the opportunity they identified and improve their chance of survival at every corner and every turn.
These lessons observed here are not commonly found in public domains, and only really shared from one founder to another. As I tried to build my first startup at the age of 25, I mostly did it in isolation without knowing any other founders at all. Looking back, so many mistakes could have been avoided, and so much time could have been saved, if I had just learned from founders who were a few years more journeyed than me.
【So if you are like me, and you wish to become a better founder and build a successful company in the future, then I encourage you to join a community like AppWorks Accelerator, where you can interact with and learn from over 1,300 founders just like Ming Ming.】