The AppWorks Accelerator FAQ (for founders applying to AW#34)


Founded in 2010 by Jamie Lin, AppWorks Accelerator is a startup community created by founders, for founders. 

Every six months, we welcome a new batch of founders who are building on the edge of what’s possible – those pushing the boundaries of technology and creating what the world has yet to imagine. Through a three-month program, and a community that stays with them long after, we equip them with the resources, mentorship, and network to turn bold visions into lasting impact.  

We know there are many considerations for founders when applying to an accelerator. That’s why we’ve created an FAQ page to help you decide whether or not AppWorks is the right fit for your startup. 

As of November 9, 2026, AppWorks #34 is open for applications. You can find important information about the Accelerator experience on our main page.

The FAQs

1. What do I need to know before joining the accelerator? What is AppWorks doing to help founders make the most out of the accelerator?

We understand the unique needs and aspirations for founders, and we’re committed to providing an experience that’s both flexible and deeply supportive: 

  1. Tailored Events for Founders: No two founder journeys are alike — whether you’re just getting started, actively scaling, based in Taiwan, or operating from anywhere in the world, we’ve designed a flexible accelerator that blends online and offline experiences. You’ll have access to the resources, mentorship, and connections that best fit your unique path, ensuring that you get what you need, when and where you need it.
  2. A Pan-Asia Founder Network: Our founder and investor network spans nine markets across Asia, so wherever you are, you’ll find peers, mentors, and partners who can share local insights and open doors to cross-border opportunities.

  3. Taiwan: Your Strategic Base for Innovation: Taiwan stands at the intersection of technology, manufacturing, and finance, making it an ideal base for founders building in AI, manufacturing, defense technology, on-chain banking, and post-quantum cryptography.

    Its world-class engineering talent, reliable manufacturing partners, and robust supply chain give startups the speed and stability to develop and scale products efficiently. Combined with an open, innovation-friendly environment and strong digital infrastructure, Taiwan provides everything you need to move from prototype to market with confidence.

    We encourage founders to join our in-person activities whenever possible. Face-to-face engagement within our community in Taiwan and across Asia builds deeper relationships, sharper insights, and opportunities that online meetings cannot fully replicate.

Your success is at the heart of what we do. We can’t wait to embark on this journey with you.

2. I already raised a Series A / I’m profitable, is AppWorks right for me?

The short answer is, yes!

The long answer is, reaching a funding goal can be a cause for celebration, but it’s also a relatively minor part of the founder journey. When we admit founders into the program, it is because we have carefully considered what they need as a founder, and how our resources and network across Asia can help them grow. 

Joel Leong and Henry Chan at ShopBack had already built a business model and received seed funding in 2015 when they launched in Singapore before they came to AppWorks Accelerator #13 in 2016. 

Joel told us that had the team known about Taiwan’s massive e-commerce market (online retail sales have since reached a record over US$20 billion, in 2025) and all the region-wide technical and tactical innovations that it would eventually yield, they would have made the move to Taiwan much sooner. Taiwan has since become one of ShopBack’s biggest markets and R&D centers. It demonstrates that funding rounds and business model maturity do not limit founders in learning something new. 

As long as you think that AppWorks can help you in the entrepreneurial learning process, you should apply. 

3. What is an RFS? What kind of support can AppWorks Accelerator provide for startups in AW#34 RFS#1: Manufacturing AI, RFS#2: Defense Tech, RFS#3: On-Chain Banking, and RFS#4: PQC?

A Request for Startups (RFS) highlights the specific problem spaces AppWorks is most focused on each batch – areas we believe have strong growth potential and for founders to make a meaningful impact.

An RFS is not a restriction; it’s a signal. It helps founders understand where AppWorks can provide the most value and resources in this batch. If you’re already building in one of these areas, we’d love to meet you. But even if not, as long as your startup aligns with our focus or could benefit from joining the AppWorks founder community strategically, you are very welcome to apply.

For AppWorks #34 (AW#34), we’re looking for founders building in Manufacturing AI, Defense Tech, On-Chain Banking, and PQC — four verticals that will redefine Asia’s industrial and economic foundation in the coming decade, and where Taiwan and the AppWorks community can provide a unique advantage.

AW#34 RFS#1: Manufacturing AI

Over the past two years, the rapid progress of AI has begun to fundamentally reshape manufacturing — from design and production to operation and maintenance. Now is the time for the industry to embrace intelligent transformation.

With Taiwan’s world-class manufacturing and supply chain ecosystem, AppWorks helps founders directly connect with leading OEMs, manufacturers, and cross-industry partners to co-develop and validate PoCs, as well as build AI-driven solutions for automation, quality inspection, and predictive maintenance.

Our community already includes startups deeply rooted in manufacturing innovation, such as Innowave Tech (AW#32), building semiconductor AI agents for automated defect inspection and yield optimization; Relajet (AW#17), which delivers advanced sound separation for smart acoustics; and Groundup.AI (AW#27), which enables predictive maintenance through acoustic monitoring.

Through collaboration, sales partnerships, and shared know-how within our network, AppWorks helps your solution validate faster, scale faster, and reach real-world impact.

AW#34 RFS#2: Defense Tech

In an era of geopolitical uncertainty and growing emphasis on supply chain and technological sovereignty, dual-use technologies such as unmanned systems, sensing, cybersecurity, AI models, and advanced materials are becoming critical to both national and industrial resilience. This shift is also creating unprecedented opportunities for startups innovating in high-barrier sectors.

AppWorks Accelerator, together with Wistron Accelerator, has long focused on hardware, AIoT, and deep tech, providing a full-scale environment for manufacturing, prototyping, and validation.

Our community already includes deep-tech startups delivering cutting-edge solutions across both defense and commercial domains — such as Aliena (AW#30), developing propulsion systems for small satellites; Aonic (AW#30), Southeast Asia’s largest industrial and agricultural drone operator; Mapxus (AW#30), offering precision mapping and geospatial intelligence; and Hyarks (AW#32), which deploys autonomous fleets of unmanned marine vessels and drones for ocean data, offshore, and defense operations.

Through this ecosystem, AppWorks helps founders connect with manufacturing and enterprise partners, develop and test PoCs, access investors and R&D talent, and accelerate both technological development and market adoption.

AW#34 RFS#3: On-Chain Banking

We believe the future of finance will be programmable, transparent, and borderless, and that the next generation of banks will be born on-chain. 

Stablecoins are becoming core financial infrastructure: supply now exceeds US$300 billion, and businesses increasingly use them for cross-border payments and treasury. Regulation has arrived too: the US signed the GENIUS Act in July 2025, Hong Kong’s Stablecoins Ordinance took effect that August, and Taiwan passed its Virtual Asset Service Act in June 2026, giving stablecoin issuance a legal basis.

AppWorks is looking for founders bringing core banking services on-chain: stablecoin payments and cross-border settlement, on-chain accounts and lending, asset tokenization, and compliance and risk tools. With its dense cross-border trade and underserved SMEs, Asia is the best place to start.

Our community already includes on-chain finance pioneers such as StraitsX (AW#18), a MAS-licensed stablecoin infrastructure provider; XREX (AW#17), a blockchain-driven financial institution regulated in multiple markets; and Pendle (AW#20), which tokenizes and trades future yield. 

Through deep collaborations with leading financial institutions, telecom operators, and exchanges in Taiwan, we help you run PoCs in a regulated environment, while our FinTech, LegalTech, and Web3 founders and mentors across nine Asian markets share first-hand experience on licensing and compliance. More than 300 tech companies in our community operate across markets and are real users of cross-border payments and business finance.

AW#34 RFS#4: PQC 

The cryptographic foundations protecting the global digital economy are mathematically vulnerable to quantum computers, and the threat is closer than most assume.

Three signals point the same way. First, the bar for breaking today’s encryption keeps dropping: Google’s recent research has cut the number of qubits needed to break RSA and the elliptic-curve cryptography behind Bitcoin and Ethereum by roughly 20x, and Google itself has set 2029 as its internal PQC migration deadline. Second, regulators have set deadlines: NIST’s draft guidance would disallow RSA and ECC by 2035, and Taiwan’s Financial Supervisory Commission is targeting full PQC migration for the financial sector by the same year. Third, the attacks have already started: “Harvest Now, Decrypt Later” attacks, where encrypted data is stolen today to be decrypted once quantum computers mature, are widely believed to be underway.

Taiwan is uniquely positioned to lead this transition. Taiwanese semiconductor companies are already producing PQC-hardened hardware at scale: Winbond announced it was the first memory vendor in the world to integrate PQC into its secure flash, now deployed across IoT, industrial, server, and critical infrastructure applications. AppWorks’ own community includes Chelpis Quantum (AW#10 / Wistron Accelerator #5), a PQC migration specialist working with the financial sector to drive PQC migration, and fellow migration player PQStation (AW#33), whose platform maps an organization’s cryptography, flags quantum-vulnerable assets, and plans the migration. On the hardware side, Qinvicta (AW#33) develops PQC silicon IP for quantum-resilient security chips.

The verticals where PQC is most urgently needed: finance, telecom, manufacturing, and defense — map precisely onto AppWorks’ LP base and ecosystem. For founders building the security layer that every other industry will depend on, there is no better time, and no better place to start, than Asia right now.

Whether you’re building the next-generation AI factory, advancing dual-use technologies, constructing the foundation of on-chain finance, or pioneering the quantum-safe security infrastructure of tomorrow, AppWorks is more than an accelerator — we’re your strategic partner for entering Taiwan and scaling across Asia. Helping you go from prototype to scale, from the lab to the real world.

4. How does AppWorks Accelerator help founders enter new markets?

Since 2010, AppWorks has made close connections within founder communities and throughout the venture capital ecosystem. When startup teams decide to enter a new market, we can quickly help them learn from local partners to tap into key resources and business models that are specifically tailored to different regions.

Today, the AppWorks community brings together over 650 active technology startups, of which more than 300 operate across multiple Asian markets. The network spans founders from Singapore, Indonesia, Vietnam, the Philippines, Malaysia, Korea, Japan, Hong Kong, and Taiwan—ensuring that wherever you plan to expand, there’s already an AppWorks founder community on the ground ready to exchange insights, share local know-how, and open doors.

This community is supported by a strong layer of mentors, alumni founders, and seasoned operators, many of whom have built, scaled, or exited successful companies. Together, they form a trusted network that helps new founders navigate everything from product localization to cross-border partnerships.

Beyond the founder network, AppWorks actively invests in over 25 venture funds across AI and Web3, including AC Ventures, Golden Gate Ventures, Openspace Ventures, Digital Garage, Ascend Vietnam Ventures, Figment Capital, and Pantera Capital. This extended capital network gives founders exposure to top investors and potential follow-on funding partners throughout Asia.

AppWorks also partners with leading corporate LPs across manufacturing, finance, media, and telecommunications. Our funds are backed by institutions such as Malaysia’s sovereign wealth fund and Korea’s government investment agencies, giving our founders privileged access to regional corporates, pilot opportunities, and distribution networks.

5. What does AppWorks look for in applications?

When AppWorks reviews applications submitted by founders, we pay special attention to a founder’s north star. Some questions that might help you think about whether AppWorks is a good fit for you: 

  • Why did you launch your startup?
  • What problem do you want to solve and why?
  • What do you believe fundamentally needs to exist in this world that doesn’t already?
  • What kind of future do you want to create and how will you get there?
  • What have you already done to demonstrate your commitment to tackling this problem?

AppWorks Accelerator’s online application covers about 30 topics related to team background, product/service, business model, market analysis, and more. It is very detailed and requires time to complete. It also includes a required one-minute self-intro from the founder (CEO) for us to know you better.

6. Does AppWorks Accelerator cost anything?

No. AppWorks Accelerator has always been free for founders. We will not charge rent or service fees, nor will we require any form of compensation, such as sweat equity, tokens, options, revenue, or profit-sharing. Our exclusive mission is to help founders. 

7. We need funding now, can we get an investment by joining AppWorks?

The short answer is you will have much better access to us than non-AppWorks accelerated teams. We will discuss with you and help you figure out at this stage of your startup’s journey if capital can give your startup a significant edge and/or take it to the next level, or if there are other more burning issues, e.g., achieving stronger product-market fit, figuring out a working go-to-market strategy, recruiting a solid co-founder, etc. 

Any AppWorks founder is welcome to start a discussion with us on fundraising anytime. We will do our best to advise and support you with US$ 386 million in total fund size behind us. 

8. My service (or product) has not yet started to make money. Can I still apply?

Of course! There probably isn’t a better time to learn in an accelerator than as a founder just starting out. This period before a founder has built a startup into a scalable business model with Product-Market Fit is called the “seed stage.” During this period, founders always need more than funding; they need a variety of entrepreneurial-related insights, inspiration from other founders, and room for trial and error. AppWorks Accelerator, with over 16 years of experience, was built to provide these lessons and more. 

9. I’m planning to expand my business into Taiwan, however, since I am not a Taiwanese citizen, can you help me obtain a proper visa?

International founders admitted to AppWorks Accelerator, according to your qualifications and needs, AppWorks can help with your application for the Gold Card, or Entrepreneur Visa in Taiwan. This enables founders from overseas to concentrate on work in Taiwan without traveling abroad to sort out troublesome visa issues. We can offer guidance on this process.  

10. Do I have to set up a company to join AppWorks Accelerator?

Not necessarily, but we recommend founders to set up an office when entering a new market, especially those of you that are B2B facing. This may enable you to build relationships with business partners and make negotiating commercial agreements smoother in the future.

For the founders who are planning to land in Taiwan, AppWorks has professional accounting and legal specialists who can assist in managing the necessary procedures, making the process of setting up much easier and more efficient.

11. What is the difference between applying during the first round vs. the final round? 

The application period is split into two intakes, with interviews and admissions facilitated on a rolling basis. Based on past experience, teams that submit their application earlier tend to have a higher chance of being admitted and are also immediately granted access to all the resources that AppWorks Accelerator has to offer. For AW#34, the first round closes on November 29, 2026, and the final round closes on December 27, 2026.

12. I have previously applied to AppWorks and have been rejected, can I apply again? Will it affect the chances of admission?

Reapplying represents the determination of the founder and is a positive signal for us. Therefore, we will re-evaluate all aspects, not only for the growth of the founder but also for the progress of the company. In the past, some entrepreneurs applied 2-3 times before being selected. In some cases, after unsuccessful applications, they continued to explore and eventually achieved more user growth and deeper insights. In other cases, they honestly faced the fact that there was no Product-Market Fit (PMF), changed their topic, found a scalable business model, and reapplied. These entrepreneurs have performed well after graduating from the accelerator.

We hope the above FAQ can help clarify your questions about AppWorks Accelerator. If you seek more clarity, please write to: [email protected], and we will try to answer your questions.

If you’re a founder creating what the world doesn’t know it needs yet, you’ve come to the right place! Applications for AppWorks #34 will be open until December 27, 2026.
AppWorks Accelerator FAQ 創業者常見問題回覆 (為 AW#34 申請團隊準備)


AppWorks Accelerator 在 2010 年由 Jamie  林之晨等創業者,為創業者所成立。每半年招募一屆,每一屆 program 為期三個月,對象是來自台灣、亞洲與世界各地的新創團隊。成立 16 年以來,AppWorks Accelerator 總共已招募 33 屆,自 2026 年 11 月 9 日起,開放申請的第 34 屆 (AW#34),將特別聚焦在站在科技最前線、致力於改寫產業規則與突破現況的創業者,並邀請正在打造智慧製造(Manufacturing AI)、國防科技(Defense Tech)、鏈上金融(On-Chain Banking),以及後量子密碼學 (PQC) 相關應用的新創團隊加入。

每次招募團隊,AppWorks 都會收到許多申請書,過程中我們發現,新創團隊在看完網站的介紹後,對我們的加速器計畫仍有些許疑問,因此,我們整理了以下常見問題,希望能為有類似疑惑的你,提供一些解答。

【AppWorks #34 自 2026 年 11 月 9 日開放申請】

  1. 在加入加速器之前,我需要了解什麼?AppWorks 在幫助創業者充分利用加速器方面做了哪些工作?

AppWorks 致力於提供創業者彈性且全面的體驗,服務台灣本地創業者、以及國際創業者。以下是一些我們獨有的特點:

專為創業者打造的活動:無論你正處於初步驗證、產品開發,還是正在擴張成長,我們都會依照創業階段,設計最適合的活動,協助你持續突破下一個里程碑。

AppWorks 的創業者來自台灣、亞洲、美國及全球各地,為了滿足跨時區與多元需求,我們提供實體與線上並行的活動形式,讓你能以最適合自己的方式參與。從工作坊、創業者對談,或是商業媒合,每場活動都經過精心設計,幫助你在每個關鍵時刻加速成長。

亞洲創業網絡:經過 16 年的持續耕耘,我們可以很自豪地分享,AppWorks 已串連起亞洲最活躍的創業生態系,包括創業者社群與投資網絡,遍佈台灣、新加坡、香港、印尼、越南、菲律賓、馬來西亞、韓國與日本,確保你無論身在何處,都能獲得需要的支持。

台灣的市場能量:台灣是亞洲科技創新的核心樞紐,擁有完整的硬體製造鏈、強大的工程與研發人才,以及開放成熟的科技環境。這裡不只是電子與半導體重鎮,更是 AI、國防科技與金融創新的理想實驗場。

AppWorks 深耕台灣超過 16 年,擁有最廣泛且活躍的在地網絡,串連企業龍頭與製造商、創投,以及頂尖學術機構。我們幫助創業者連結供應鏈資源、共同開發解決方案,並加速進入區域市場。

我們強烈建議創業者親自參與 AppWorks 在台灣與亞洲各地舉辦的實體活動,透過面對面的交流,建立更強的關係與更深的洞察,獲得真正能推動成長的連結。

  1. 什麼是 RFS?AppWorks Accelerator 可以分別提供 AW#34 RFS#1: Manufacturing AI, RFS#2: Defense Tech, RFS#3: On-Chain Banking,以及 RFS#4: PQC 新創什麼幫助?

RFS (Request for Startups) 是我們在每一期加速器中特別關注的主題,代表我們認為具有發展潛力、值得優秀創業者投入的方向。RFS 不是限制,而是我們希望創業者留意的訊號,讓創業者了解 AppWorks 此期聚焦的重點與我們能提供的資源。

如果你的創業題目正好屬於這些關鍵領域,我們很期待認識你;若不是,但你認為自己的解決方案與我們關注的方向相契合,或者相信加入 AppWorks 社群將能帶來策略性的成長,也同樣非常歡迎申請。

AppWorks 正在尋找致力於 智慧製造(Manufacturing AI)、國防科技(Defense Tech)、 鏈上金融(On-Chain Banking),以及後量子密碼學(PQC) 的創業者。我們相信,這四個領域將在未來十年改變亞洲的產業結構與經濟基礎,也是台灣與 AppWorks 的社群能為創業者發揮助力的地方。

AW#34  RFS#1: 智慧製造(Manufacturing AI)
過去兩年 AI 的加速發展,讓我們看到了 AI 正全面改變製造業的運作模式,從產品設計、生產製程,到後續維運,皆有機會被大幅翻轉 – 現在正是製造產業迎向智能化升級的關鍵時刻。

台灣擁有世界級的製造與供應鏈生態系,AppWorks 能協助創業者直接連結頂尖 OEM、製造商與跨產業夥伴,共同驗證 PoC、開發 AI 驅動的自動化、品質檢測與預測維護等實際應用。

同時,我們的社群中已聚集眾多 AI 與製造相關的新創,例如為半導體廠打造 AI Agent,自動執行瑕疵檢測與機台操作的 Innowave Tech (AW#32)、提供精細音訊分離技術的 Relajet (AW#17)、以聲音監測進行預防性維護的 Groundup.AI (AW#27) 等等。透過彼此共同開發、銷售或是經驗分享,AppWorks 社群能幫助你更快驗證、更快落地,推動產品從原型走向規模。

AW#34  RFS#2: 國防科技(Defense Tech)
在地緣政治緊張、各國追求供應鏈與關鍵技術自主的時代,具「雙重用途」的科技—如無人系統、感測、資安、AI 模型與新材料,正快速成為維護國家與產業安全的關鍵力量;這同時也代表著新創能以創新技術切入高門檻市場的機會。

AppWorks 加速器、以及我們與緯創集團共同運營的緯創加速器(Wistron Accelerator),長期聚焦於硬體、AIoT 與深科技領域,提供從製造生產到概念驗證的場域。

同時,我們的社群中已有多支深科技新創,提供國防與商業最前沿的科技應用。包括打造航太與小型衛星推進技術的 Aliena (AW#30)、東南亞最大的農工業無人機服務供應商 Aonic (AW#30)、提供高精度定位與地圖資料解決方案的 Mapxus (AW#30),以及結合無人船與無人機、瞄準遠洋與國防商機的海洋數據平台 Hyarks (AW#32) 等等。

在這樣的生態網絡中,AppWorks 將協助新創團隊媒合製造與企業夥伴,開展 PoC 與試驗合作,並連結投資人與技術人才,幫助你強化研發實力、拓展商務應用。

AW#34  RFS#3: 鏈上金融(On-Chain Banking)

我們相信金融的未來,將是程式化、透明且全球化的,而下一代銀行將誕生於鏈上。

穩定幣正在成為新的金融基礎設施:全球流通量已突破 3,000 億美元,越來越多企業用它做跨境支付與資金調度。監管也已到位:美國於 2025 年 7 月簽署 GENIUS Act,香港《穩定幣條例》同年 8 月生效,台灣《虛擬資產服務法》也於 2026 年 6 月三讀通過,明定穩定幣的發行依據。

AppWorks 正在尋找把銀行核心服務搬上鏈的創業者,包含穩定幣支付與跨境結算、鏈上帳戶與借貸、資產代幣化,以及合規與風控工具。跨境貿易密集、中小企業金融需求長期未被滿足的亞洲,正是最好的起點。

AppWorks 社群中已有鏈上金融的先行者,包括 MAS 持牌的穩定幣基礎設施 StraitsX (AW#18)、在多國受監管的區塊鏈金融機構 XREX (AW#17)、以及實現資產未來收益代幣化的 Pendle (AW#20)。

我們也與台灣的金融業龍頭、電信公司及交易所深度合作,協助你在受監管的環境中進行 PoC;橫跨亞洲九個市場的 Fintech、LegalTech 與 Web3 創業者和導師,能分享牌照與合規的第一手經驗;社群中超過 300 家跨市場經營的科技公司,更是跨境收付與企業財務的真實用戶。

AW#34 RFS#4:後量子密碼學(PQC)

量子威脅來得比多數人預期更快,從三個訊號就能看出:第一,破解門檻大幅下降。Google 近兩年的研究,已將破解 RSA 與比特幣、以太坊所用橢圓曲線加密所需的量子位元數下修約 20 倍,Google 自己也把 2029 年訂為內部完成 PQC 遷移的期限。第二,監管期限已經明確。美國 NIST 草案規劃 2035 年前全面停用 RSA, ECC 等現行演算法,台灣金管會也發布指引,目標金融業在 2035 年前完成遷移。第三,攻擊已經開始。「先竊取、後解密」(Harvest Now, Decrypt Later) 的手法被普遍認為正在發生,今天被偷走的加密資料,未來都可能被解開。

台灣在這波轉型中,擁有其他地方難以複製的條件。硬體層面,華邦電子 (Winbond) 宣布成為全球第一家將 PQC 整合進 secure flash 的記憶體廠商,產品已廣泛應用於 IoT、工業、伺服器與關鍵基礎設施領域。AppWorks 社群中也已有先行者:池安量子 (Chelpis Quantum)(AW#10 / Wistron Accelerator #5)專注於 PQC 遷移服務,正與金融業合作推動 PQC 遷移;同樣聚焦遷移的 PQStation (AW#33),則協助企業盤點加密資產、找出量子風險並規劃遷移路徑;硬體端則有開發 PQC 安全晶片矽智財 (SIP) 的 Qinvicta (AW#33)。

PQC 最迫切需要的領域:金融、電信、製造與國防,正好與 AppWorks 的 LP 網絡高度重疊。對於想打造「所有產業都將依賴的安全基礎層」的創業者而言,現在正是最好的時機,亞洲正是最好的起點。

無論你正在打造下一代 AI 智慧工廠、研發國防自主科技、建立鏈上銀行的基礎架構,或是佈局未來產業都將依賴的安全基礎層,AppWorks 的定位,並不只是加速器,而是你進入台灣與亞洲市場的策略夥伴。我們期待與你一起,從原型走向規模,從實驗室走進現場。

  1. 如果我的新創已經完成 Series A/B 募資、或是已經開始獲利,AppWorks Accelerator 還適合我嗎?

我們並沒有限定申請團隊的成熟階段,無論是正處於早期、或是已規模化擴張的團隊,只要你認為在創業過程中,AppWorks 能提供到你所需要幫助,都歡迎申請加入。

依過去的案例,也有許多較成熟的團隊加入,例如,有些團隊已經在台灣做出不錯的成績,想往東南亞發展,AppWorks 可以成為新創佈局東南亞的橋樑或跳板。

或者是規模已不小的國際團隊,如果想在台灣建立技術團隊或開發市場商機,加入 AppWorks, 可以成為在台落地的第一步。像是例如來自新加坡、在 2016 年進駐 AW#13 的 ShopBack,早在 2014 年就創立,並在 2015 年完成種子輪募資並在新加坡推出服務,而透過在 AppWorks Accelerator 的時間,ShopBack 在台灣建立起技術團隊,並同時驗證了測試台灣市場的發展性可能性。如今,台灣已是 Shopback 所有經營的市場中,重要的營收來源和核心研發基地。

  1. AppWorks Accelerator 可以提供想進入國際市場的新創什麼幫助?

AppWorks Accelerator 自 2010 年啟動迄今,累積了廣大的創業者社群與 VC 夥伴網絡,協助新創團隊在進入新市場時能快速獲取關鍵資源,並向當地的創業者學習因地制宜的商業模式。

目前,我們的社群中已有超過 650 家活躍的科技公司,其中超過 300 間已經是跨市場經營的企業。社群中不僅包含加速器校友新創與 AppWorks 基金投資的國際團隊,也有眾多曾成功規模化或退出的創業者與 Mentors。

他們分布於亞洲 9 個市場:台灣、新加坡、印尼、越南、菲律賓、馬來西亞、韓國、日本,與香港,這代表無論你想進入哪個市場,AppWorks 社群中都已有在地的創業者群體,以及曾成功拓展跨國事業的創業者,能與你交流經驗、協助引薦人脈,加速你在新市場的落地。

除了創業者社群以外,AppWorks 另外在 AI, web3 等領域投資超過 25 個創投基金,包含 AC Ventures, Golden Gate Ventures, Openspace Ventures, Digital Garages, Ascend Vietnam Ventures, Figment Capital, Pantera 等。

此外,AppWorks 與認同我們理念的基金投資人合作,其中包括在科技製造、金融、媒體、電信等領域領先的企業,基金也獲得馬來西亞主權基金與韓國政府投資機構的支持,並與印尼最大的電信公司 Telkomsel 建立合作關係,進一步鞏固我們在亞洲的布局,讓新創團隊進入新市場時,能與不同區域的投資人合作、更有效率的拓展人脈與商機。

  1. AppWorks Accelerator 要收費嗎?

AppWorks Accelerator 是針對創業者完全免費的服務。我們不會向新創團隊收取租金、服務費,也不會要求技術股、選擇權、營收、獲利分成,或是 Token 等任何形式的回饋。

  1. 我們現在需要一筆資金,加入 AppWorks 就可以被投資嗎?

相較於其他新創團隊,參與 AppWorks Accelerator 的創業者,有更多與我們深度交流的機會,自然也就有更高的合作機率。無論參與的新創處於什麼階段,我們都會與創業者討論,什麼是現階段最需要且適合你的幫助。在對的時間點,當資金可以大幅提升該新創的實力與競爭優勢,我們會全力協助你完成該輪募資。但有些時候,創業者當下更重要的任務,是解決其他更急迫的問題,包括重新定義市場問題、 探索正確的目標客群、或是尋找更強的 Product Market Fit 等等。

AppWorks 管理四支創投基金規模共 3.86 億美元,無論是關於募資,或是其他策略面向的討論,我們隨時準備好提供你最適切的建議與協助。

  1. 我的服務 (或產品) 還沒開始賺錢,這樣能申請嗎?

當然可以。從公司創立到找到可規模化商業模式這段期間,稱為「種子期」。種子期新創公司需要的多半不是資金,而是各種與創業有關的知識、啟發,以及嘗試與犯錯的空間。AppWorks Accelerator 有豐富的經驗,協助種子期新創尋找可規模化商業模式,幫助他們順利邁向下一階段。

  1. 加入 AppWorks Accelerator 一定要設立公司嗎?

不一定,但我們會建議做 B2B 的團隊設立公司。根據我們的經驗,這將有助於你與潛在事業夥伴洽談後續合作。AppWorks 有專業的會計與法務專家,可以為創業者提供成立公司過程中所需要的協助;以及為計劃擴張到台灣的團隊處理落地的手續。

  1. 9. 我不是台灣公民,能否幫忙申請簽證?

入選 AppWorks Accelerator 的國際創業者,可根據個人的需求與條件,由 AppWorks 提供協助,申請 Gold Card 就業金卡、 Entrepreneur Visa 創業家簽證 ,讓來自海外的創業者能在台灣專心工作,不需為了簽證問題出境往返。

  1. 新創的申請書中,AppWorks 注重的內容有哪些?

我們特別重視驅動創業者長期持續自我精進、沿途排除阻礙,非得要抵達的北極星。此外,以下幾個問題,也是我們關注的:

  • 為什麼要創業?
  • 你希望透過創業解決什麼問題?為什麼?
  • 你相信世界上,還有哪些尚未被滿足的基本需求?
  • 你希望創造什麼樣的未來?計畫如何去實現?
  • 你已經做了哪些努力來證明你正在解決這些問題?
  1. 申請書的題目都是英文,用中文寫會不會影響分數?

AppWorks Accelerator 的線上申請書共有約 30 個題目,包含團隊、產品、商業模式,與市場分析等眾多面向,非常詳盡,需要花一定的時間與心思填寫。我們希望透過這些題目協助每一個來申請的團隊,釐清自己當下的發展狀態與所需協助。

填寫報名表是一種自我健檢,因為在填寫過程中,創業者必須深入思考自己的產品、市場策略、團隊分工,以及整體產業環境。因此,不管申請與否,我們都建議創業者針對這些問題仔細思考、研究。

在 AppWorks,創業者有大量使用英文的機會,與各國創業者、投資人與企業夥伴溝通交流。因此,我們鼓勵你嘗試以英文作答。用中文填寫並不會影響評估結果,最重要的是必須清楚表達你想傳達的訊息。另外,我們也需要創辦人/CEO 拍攝一段一分鐘的自我介紹與產品說明影片,讓我們不僅是透過文字,能夠更加認識你。

  1. 第一階段 VS. 第二階段申請有何差別?

AppWorks Accelerator 的面談與入選採先收先審方式 (Rolling-basis),根據過去的經驗,先繳交申請書的團隊,有較高的入選機率,且能提早知道自己已經入選,有更充裕的時間預先規劃相關事宜。因此,我們會鼓勵創業者在第一階段就填寫申請書,以免到了最後申請截止前夕,競爭變得更加激烈。AW#34 第一階段申請截止日為 2026 年 11 月 29 日(日),第二階段(最終)申請截止日為 2026 年 12 月 27 日(日)。

  1. 我以前有申請過 AppWorks 被拒絕了、還能再申請嗎?是否會影響錄取的機率呢?

不會影響錄取率。我們會評估你在這段時間的進展,無論是 Founder 本身的成長,或是公司的拓展。整體而言,再次申請代表了創業者的決心,對我們來說是正面的訊號。過去也有創業者申請了 2~3 次才獲選。有的案例是在申請未果後,仍繼續耐心摸索,最終成功增長更多的用戶、也累積了更深入的洞察;有的案例則是坦誠面對沒有 PMF 的事實,更換了題目後,找到可擴展的商業模式而再次申請,而這些創業者自加速器畢業後的表現也相當優秀。

希望以上整理能幫助你釐清對 AppWorks Accelerator 的諸多疑問。若還有其他需要進一步瞭解的地方,歡迎留言給我們,或是來信至:[email protected],我們將盡量為你解答。

【歡迎所有不滿足於現狀、正致力於以嶄新方式突破傳統的創業者,加入專為你們服務的 AppWorks Accelerator,AW#34  申請截止日為 2026 年 12 月 27 日】

    The New Shape of Work

    with contribution from Natasha Chou, Alumni Relations Manager at AppWorks


    The most valuable part of working with AppWorks’ large founder community is watching founders iterate, in person, every single day. Especially since OpenClaw arrived at the start of this year, founders seem to have been handed a brand-new torch, and they are using it to find out how many previously impassable tunnels AI can lead an organisation through.

    Since April 2025, AppWorks has hosted a monthly AI Founder Circle at our Taipei office, and a bi-monthly edition has since started in Singapore where AppWorks has 98 active startups in the community. After more than ten Circles, the topics have evolved along the way: from how to use OpenClaw to how to build your own AI agent; from how to get employees to adopt AI smoothly, to building AI employees and standing up a full agent-harness platform… and now we have arrived at a new frontier: the old shape of the organisation no longer seems to fit.

    Optimising the organisation has always been a rite of passage on a startup’s growth path. Almost every company starts as an agile squad of fewer than ten people, fully aligned and all-in every day. Then, as it grows, it seems obliged to follow in the footsteps of the big companies that came before: departmentalise, divisionalise, and start to feel the growing pains. When a company first reaches a size of 100 to 200 people, it will start to experience the pain of an organisation that gets bigger while its efficiency does not.

    To build a big business, you need many hands on deck; but the more people you have, the harder they are to manage, because the bandwidth of human communication is limited. AI seems poised to relieve this millennia-old management pain: it moves information in greater volume, at greater speed, and with less of the distortion that comes from passing through many hands. 

    Pioneering founders and executives have already begun to experiment. In March, Jack Dorsey put forward the hypothesis of a fully flat organisation (see From Hierarchy to Intelligence, co-written with Sequoia Managing Partner Roelof Botha); in May, Cloudflare CEO Matthew Prince wrote in The Wall Street Journal to explain why he was laying off and replacing staff at a moment of rapid revenue growth and healthy cash flow (How I Choose Which Cloudflare Employees to Replace with AI); and in July, Jamie, our AppWorks Founder and Chairman, published 《逆分工》 (Reversing the Division of Labour) with Taiwan Mobile CIO Rock Tsai, exploring the productivity revolution of the AI era.

    In Asia, many founders are now running the same experiment, and through their first-hand experience and iteration we have had the privilege of a close-up view. In this article we put forward a hypothesis about the shape of organisations in the AI era, and invite the founders holding the torch to glimpse the future with us — and we will also explain why the new shape is only the ticket in, not the endgame. 

    We have also asked several founders, at different stages and scales, to share the experiments they are running and the results so far, so this is not merely a theory proposed by AppWorks, but the product of generous contributions from the AppWorks founder community.


    Every technological revolution reshapes how we organise

    Every technological revolution reshapes how we organise, and it has happened at least twice before.

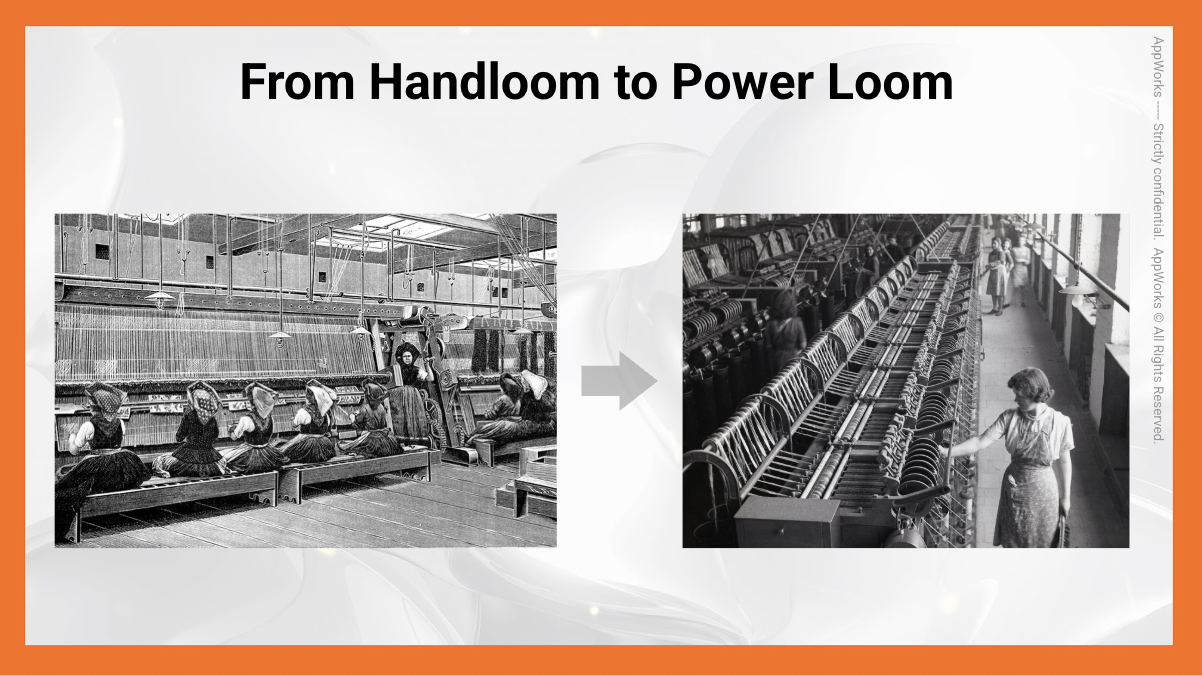
    The first time was in the textile mill. Before the 18th-century Industrial Revolution, the handloom was merely a tool; the craft lived in the weaver, one weaver per loom, and output was capped by the number of hands. When the power loom arrived, the machine absorbed the craft, and the human’s job became tending the machine. One person now oversaw an entire row of looms, and the work shifted from weaving by hand to setting the standard and catching the exceptions. Walk into a TSMC fab in 2026 and you still see this shape: the most advanced process engineer is not the craftsman of any single wafer, but the keeper of the machine’s yield.

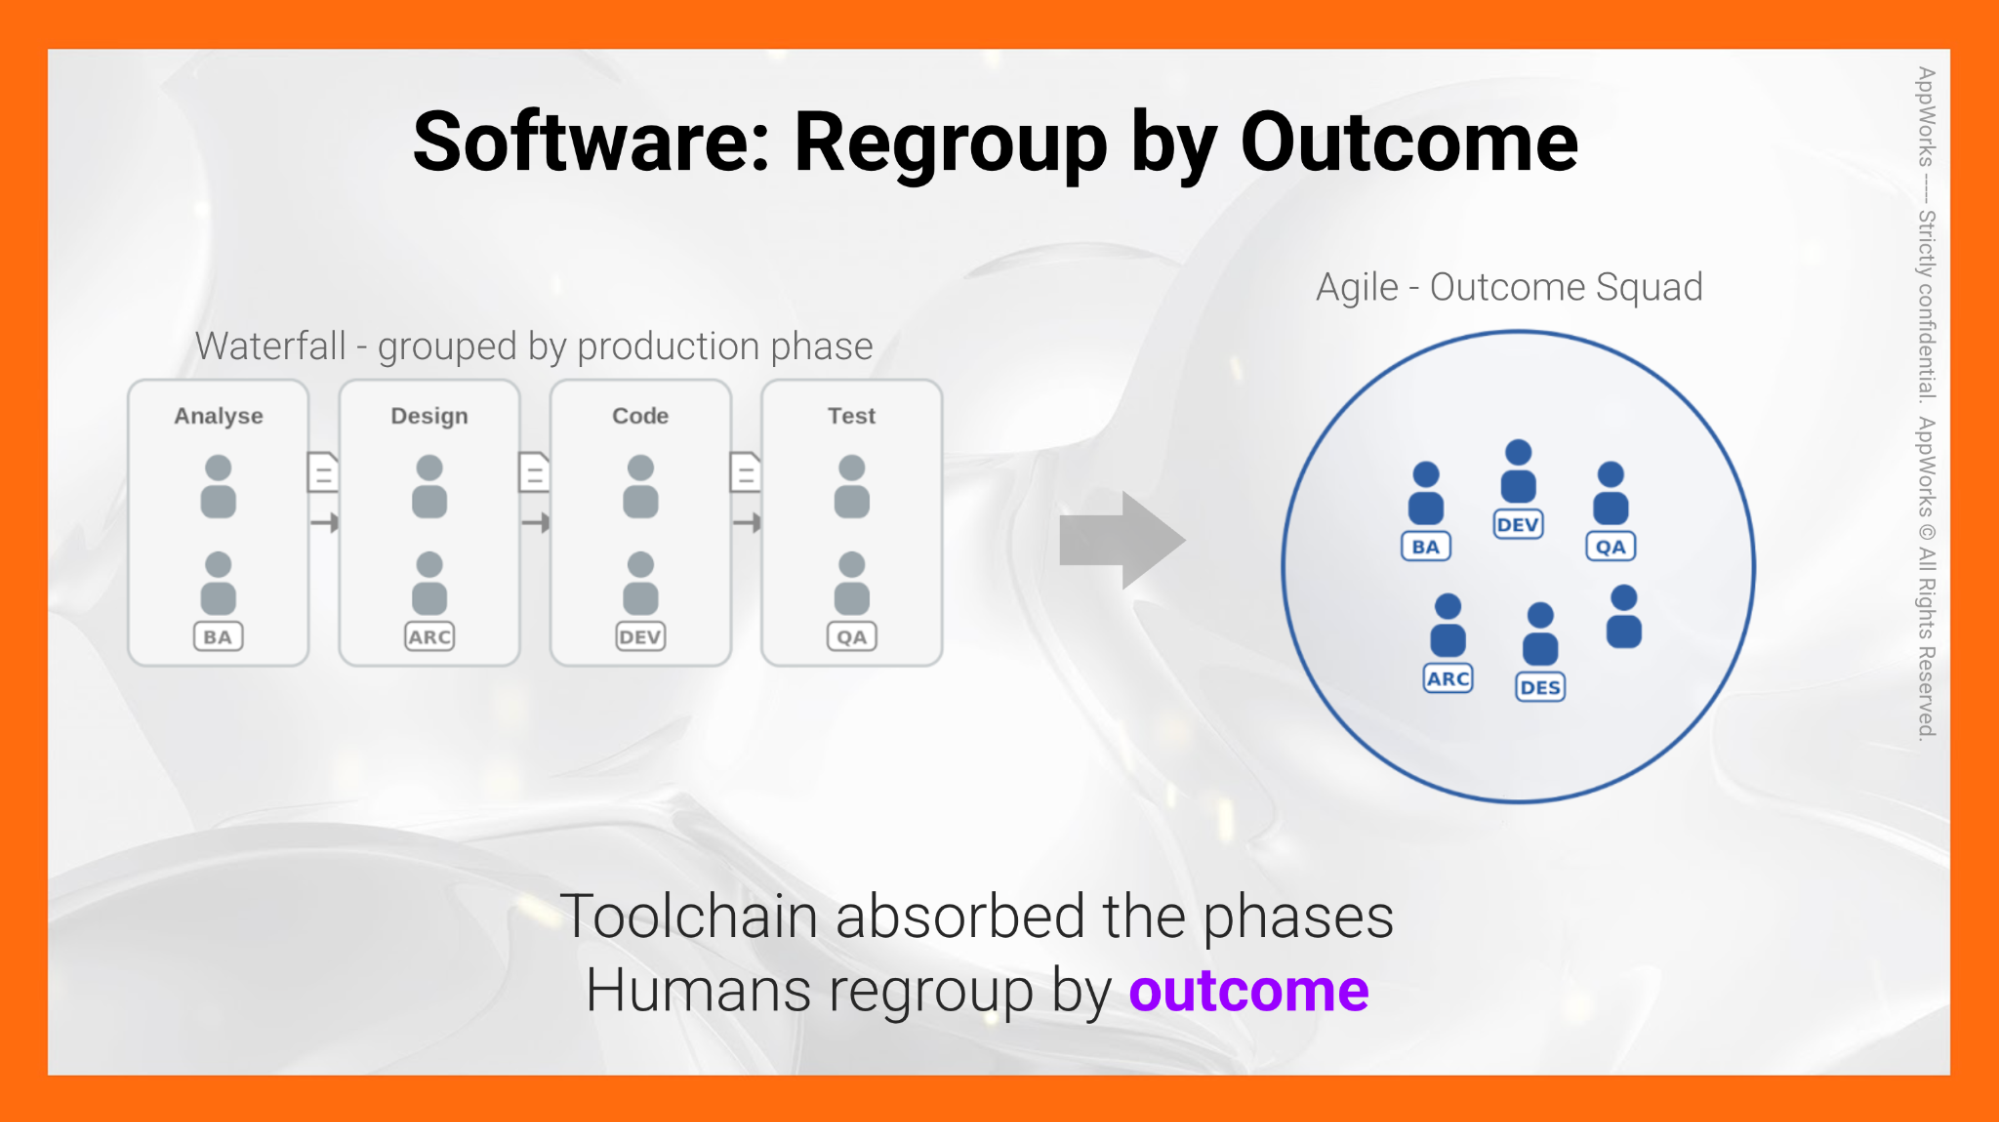
    The second time, it was software’s own turn. From mainframes to personal computers to the cloud, engineers’ tools have a peculiar property: anything that can be written down as a rule, the tool can do for you — and the first thing it took over was proving that the person before you hadn’t got it wrong. Early waterfall grouped people by process step — analysis, design, coding, testing — four departments handing off in sequence, with documents as the stitching. What that documentation really did was carry trust from one runner to the next. Once version control, automated testing and continuous integration turned verification into a machine’s job, and the cloud turned shipping from a one-shot, live-or-die event into something you could roll back at any time, the handover documents had nothing left to prove. What collapsed wasn’t labour hours; it was the cost of making mistakes and of coordinating. Change the costs and the shape reorganises to match. From roughly 2001 onwards, agile made cross-functional teams the mainstream of the software industry: product, engineering and design sitting in one small team, jointly accountable for a specific outcome like “raise homepage conversion”. (Spotify later called such a team a squad.)

    Shape never follows the prevailing ideas; it follows what actually works. That also explains a piece of industry history: over the past 25 years, agile has almost never genuinely succeeded outside the engineering teams of internet companies, because what can be moved is the ceremony, and what can’t be moved is the machine underneath it. Other departments’ systems record work; they don’t do the work, and they certainly don’t check the work. A CRM records customers, but it doesn’t talk to them, and it won’t tell you the call went badly. Without that machine, what a cross-functional team delivers doesn’t get any better — it just changes how the meetings are held. So the ceremonies stay, and the shape reverts.


    The knowledge worker’s industrial revolution

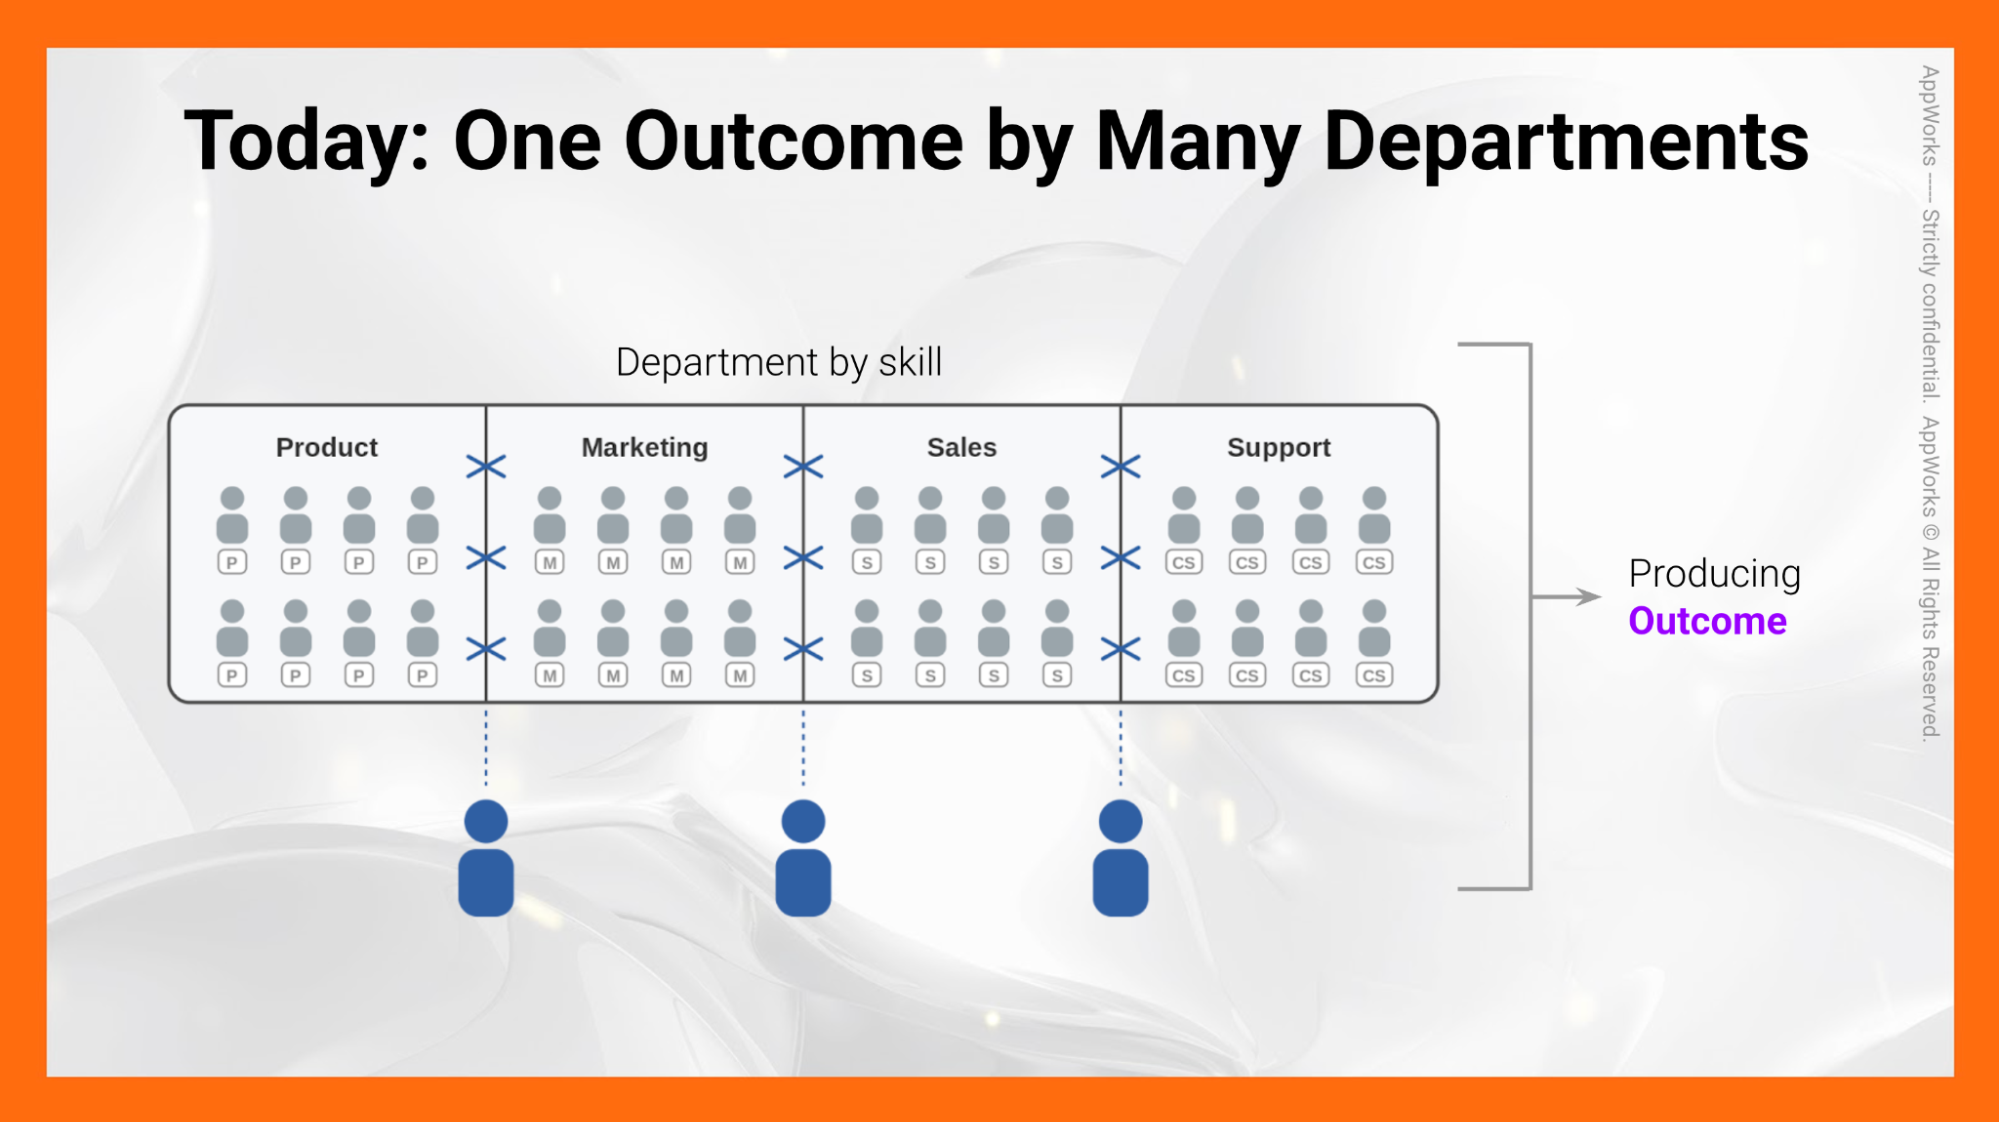
    Look at a company today. A single customer outcome is typically sliced across four departments: product, marketing, sales, and customer service. Each holds its own meetings and accountability to stay aligned. And most of a knowledge worker’s day is spent moving data between systems: from email into the CRM, from a report into a slide deck. Enterprise IT even has a formal term for this: the swivel-chair integration, swivelling this way to copy, and swivelling that way to paste. With a desk full of systems and tools, the knowledge worker is still living in the age of the handloom.

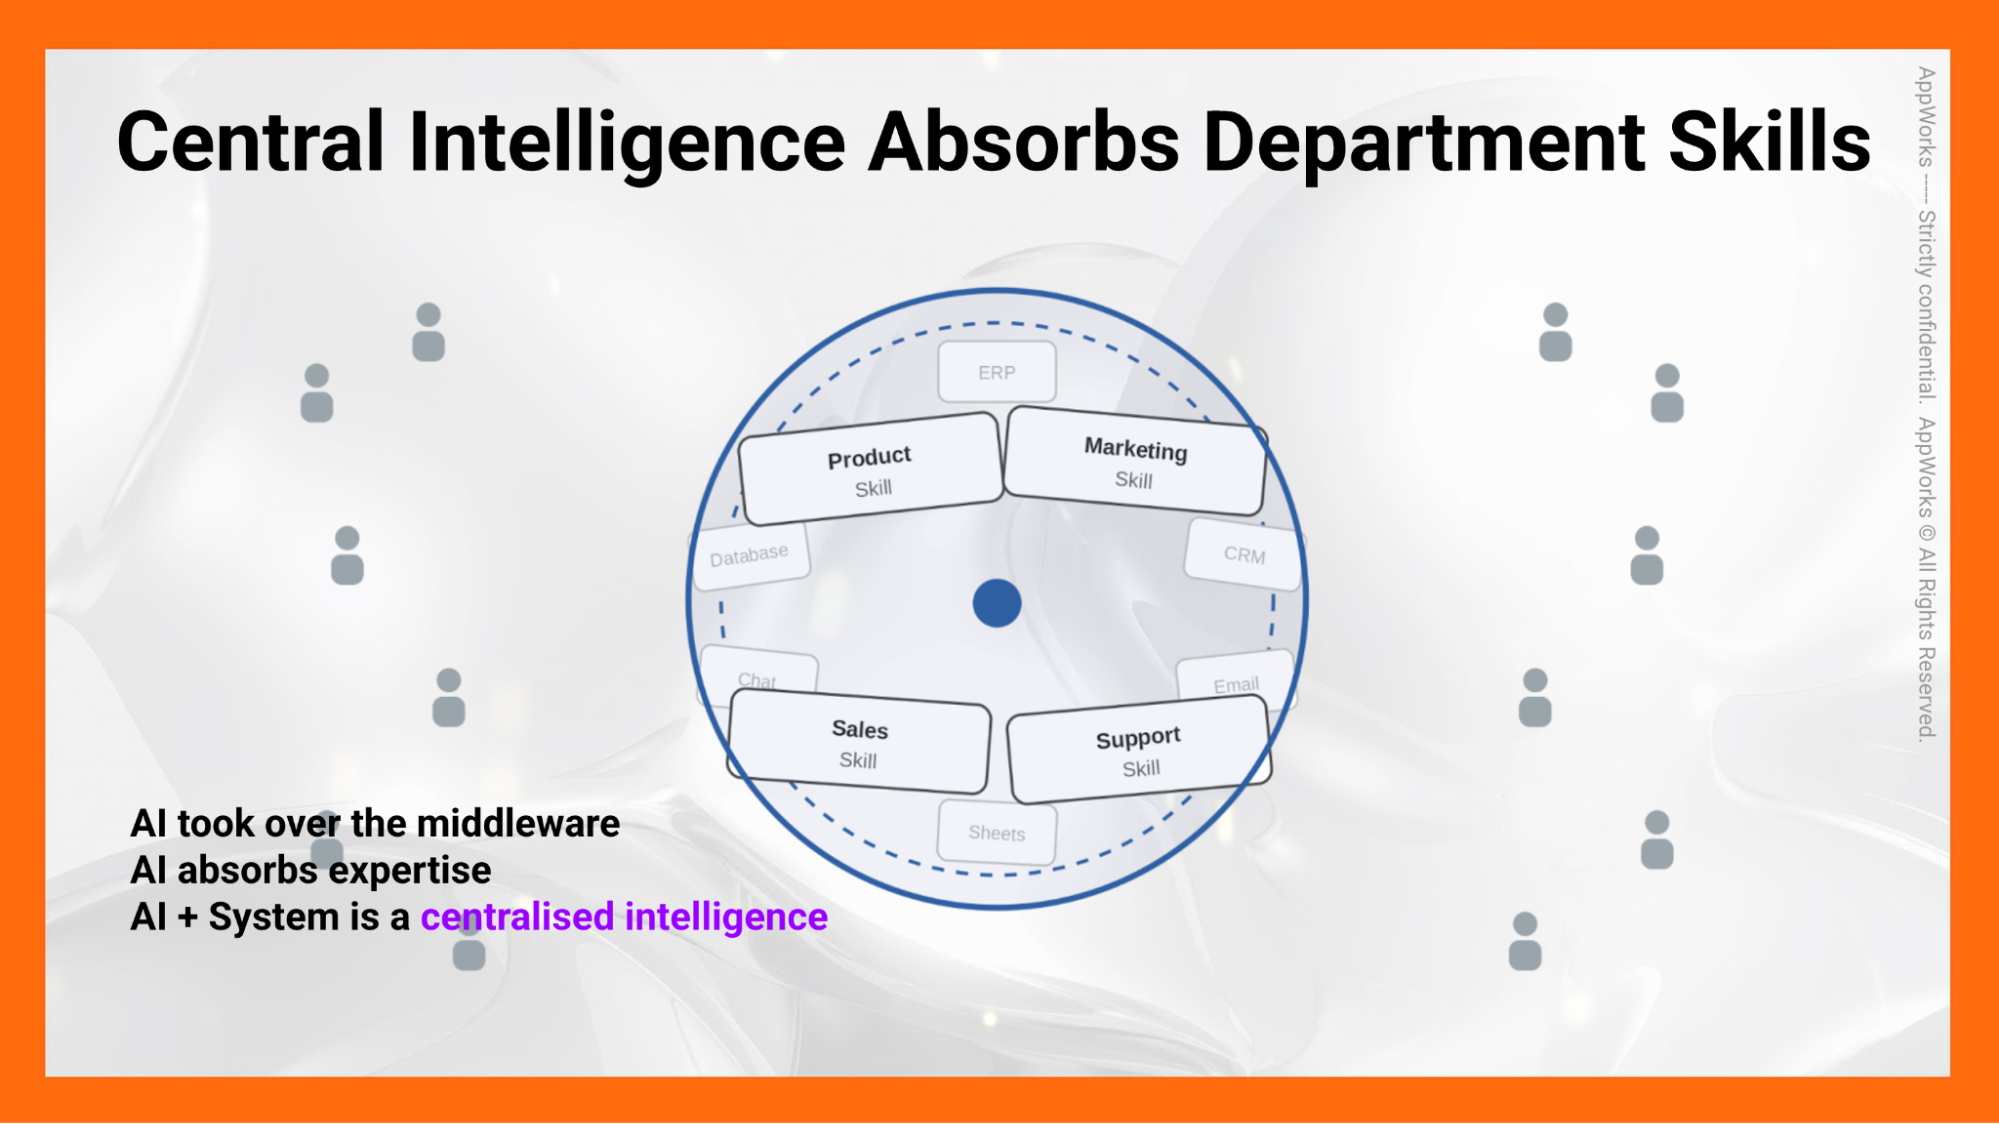
    What AI is doing to knowledge work is precisely what the power loom did to weaving: it draws the craft up into the machine. It first takes over the hauling and the stitching, and then absorbs each department’s execution as well: marketing’s ad placement, sales’ quoting, customer service’s tickets all become on-demand capabilities inside the machine. In effect, every back-office function gets an API.

    This is the industrial revolution of knowledge work. For the first time, people can truly step to the side of the machine. The next question is the hypothesis we want to discuss today: once people have stepped aside, how should they reorganise and regroup?


    Our hypothesis: The New Shape of Work

    The new shape of work is, first of all, a new shape of the organisation.

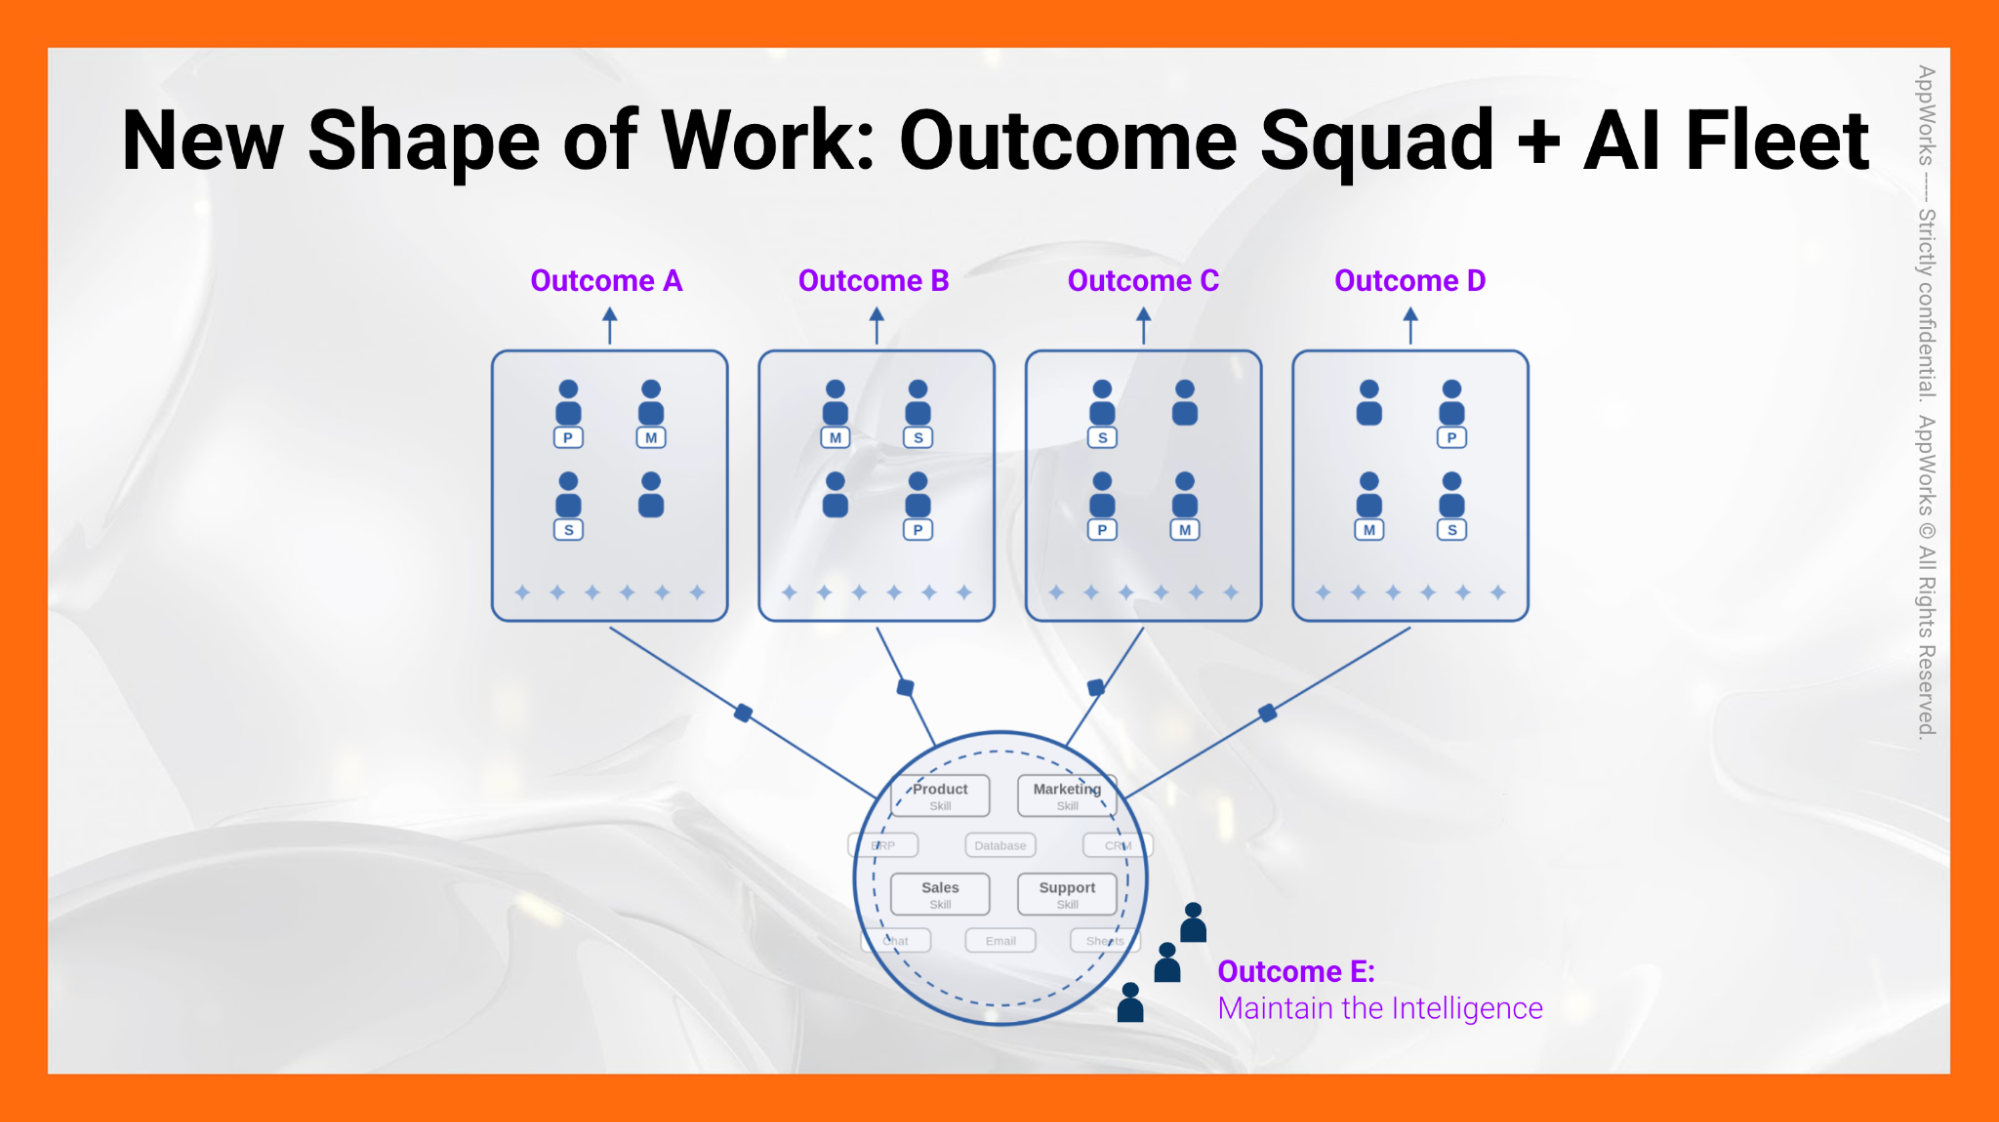
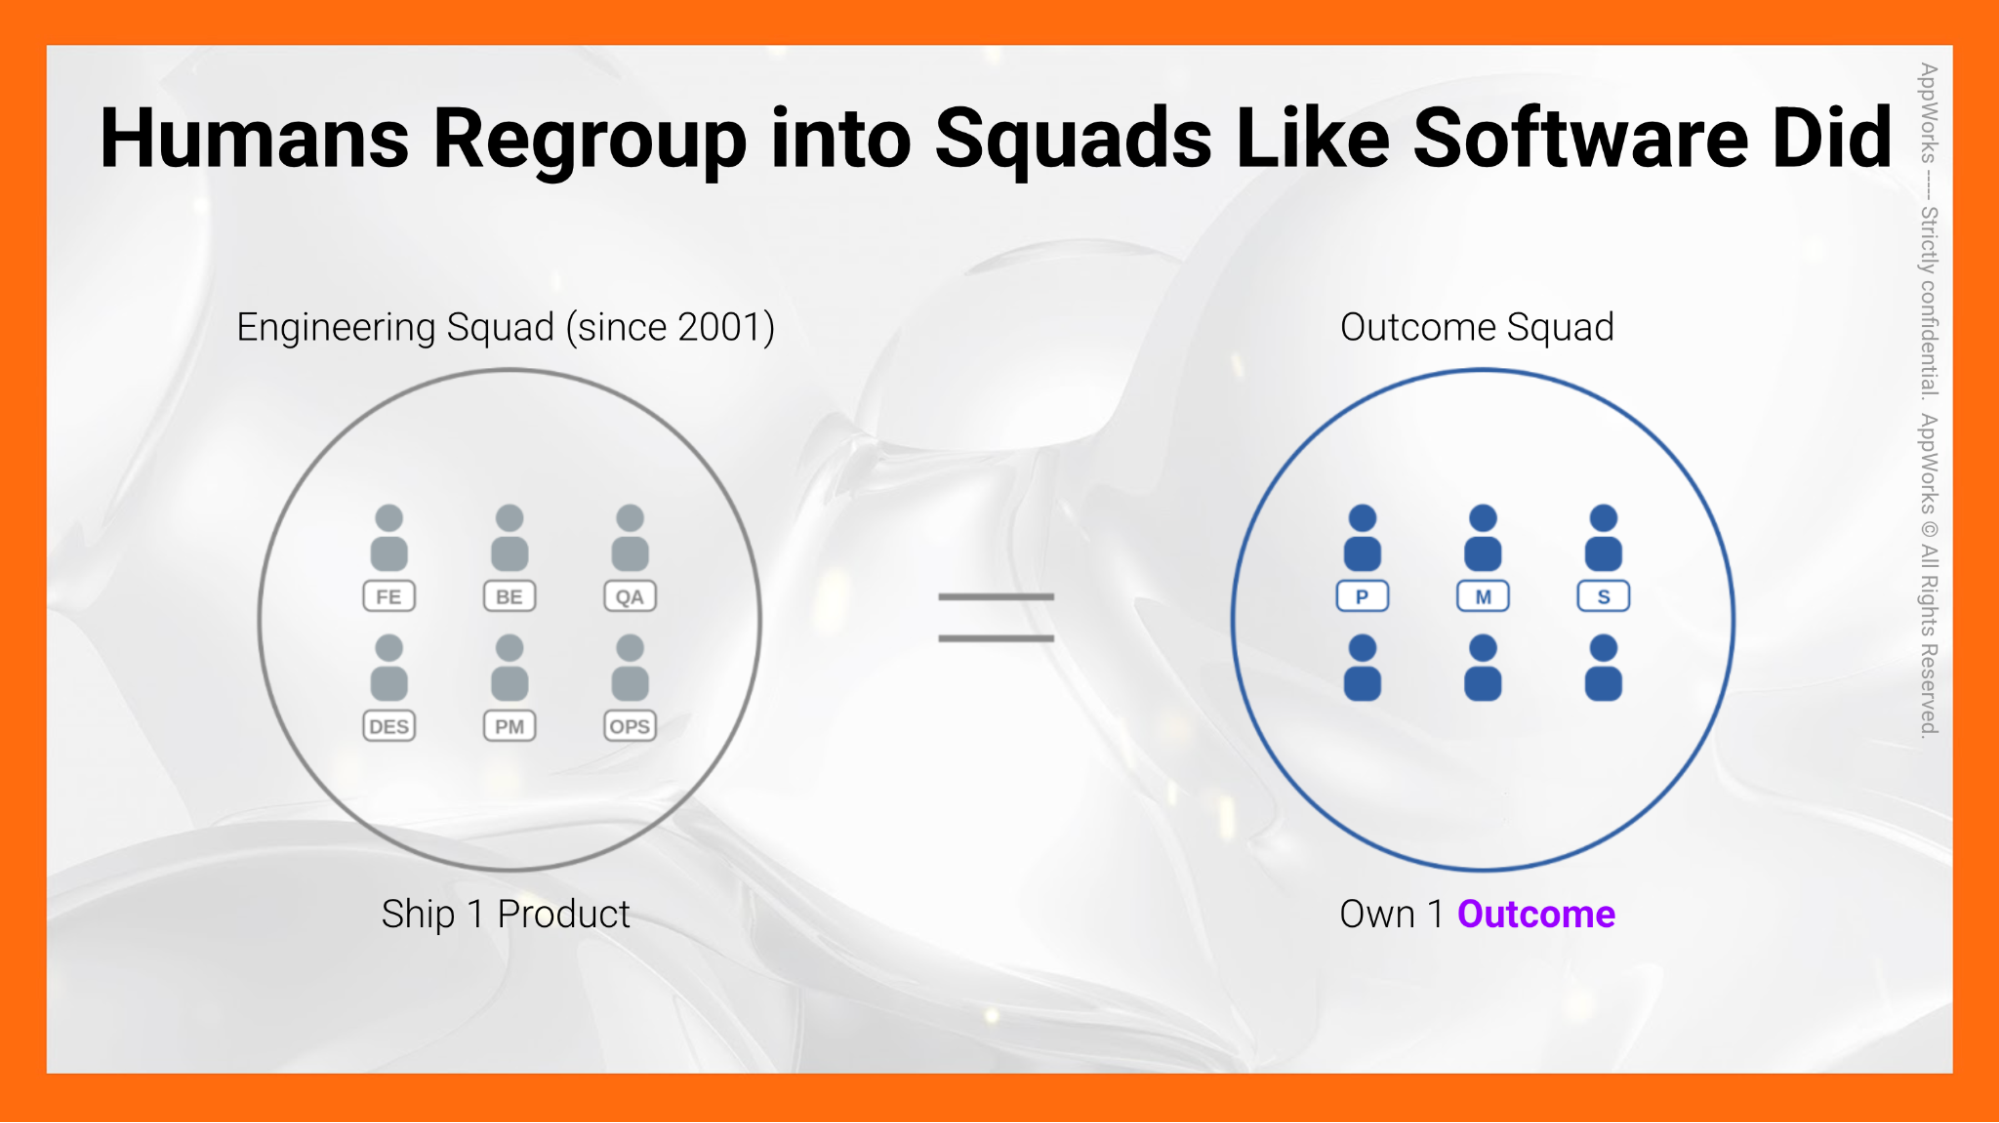
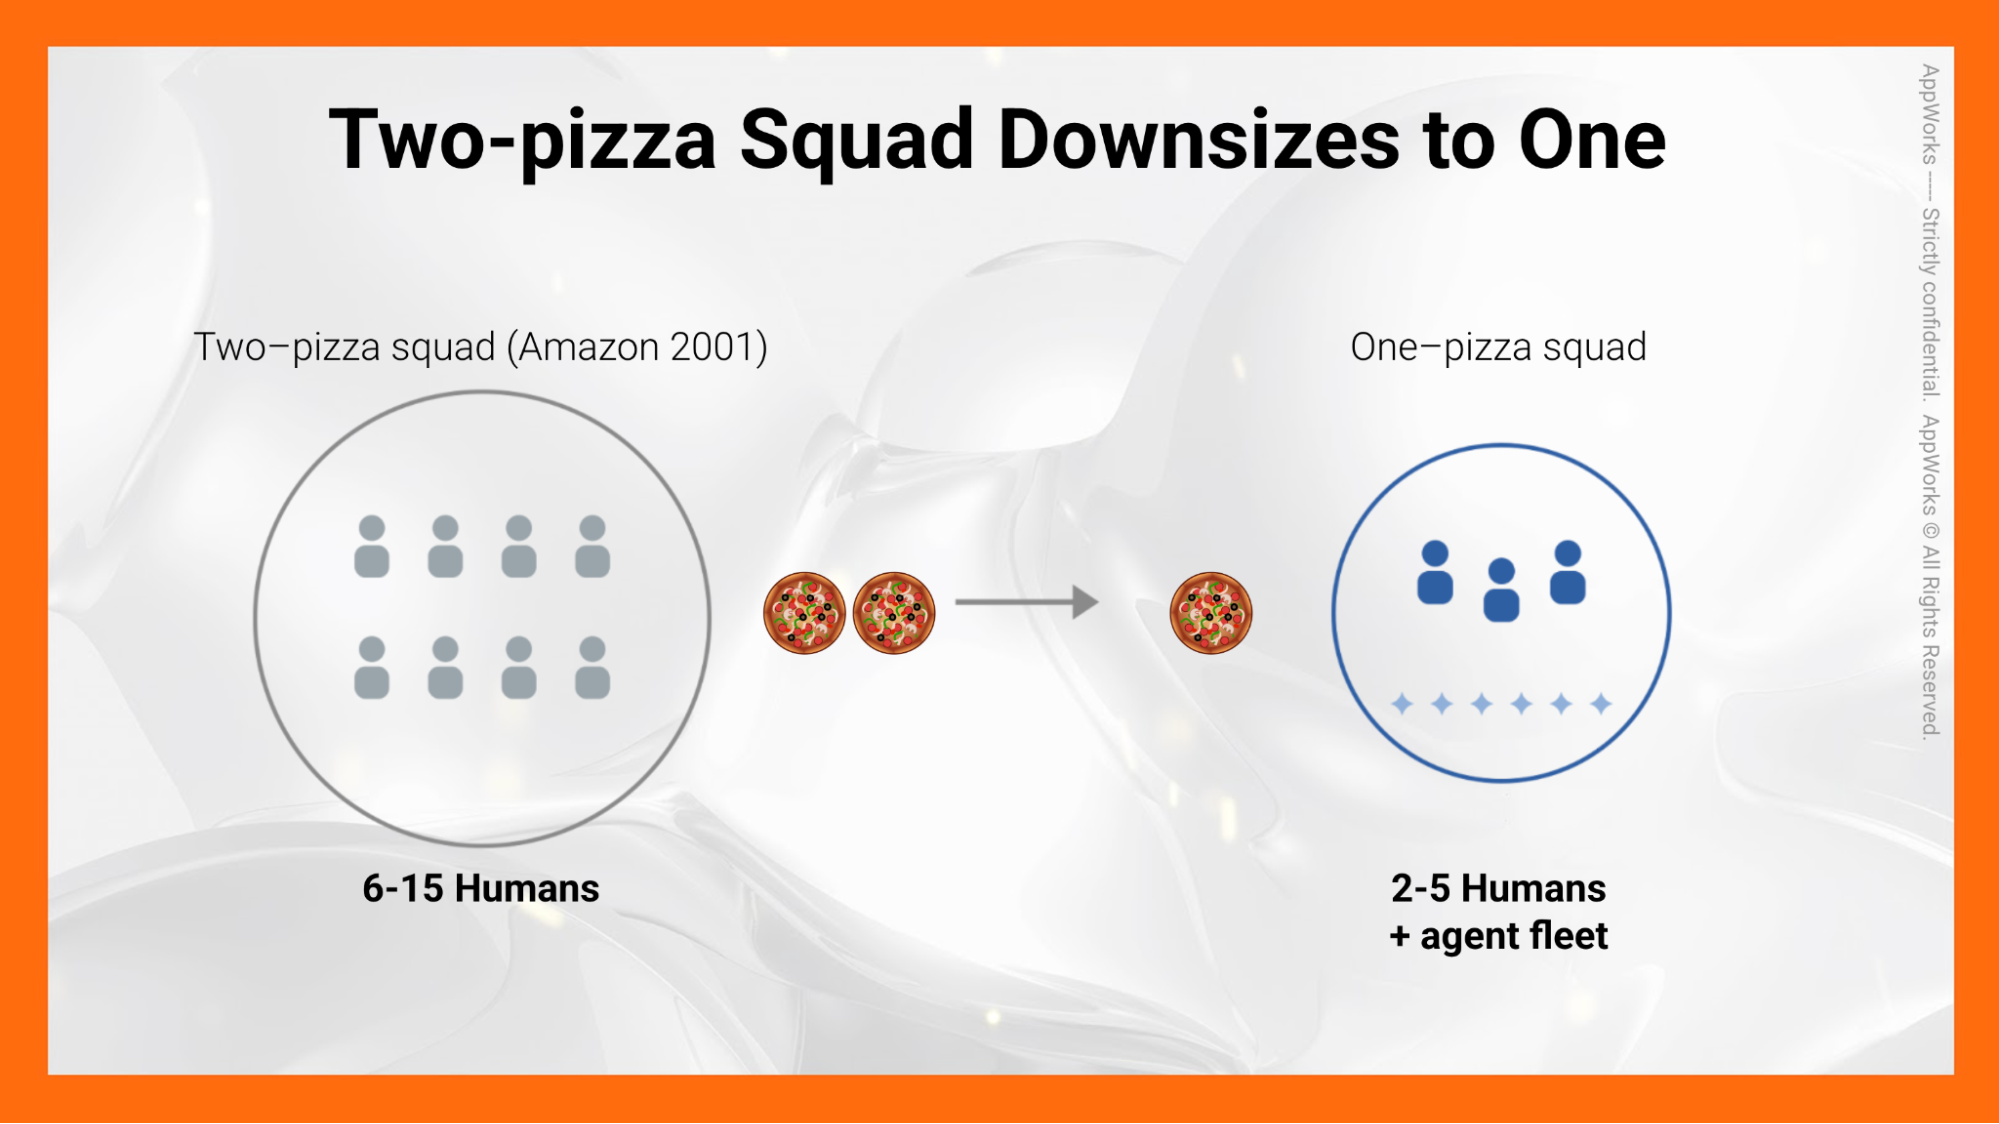
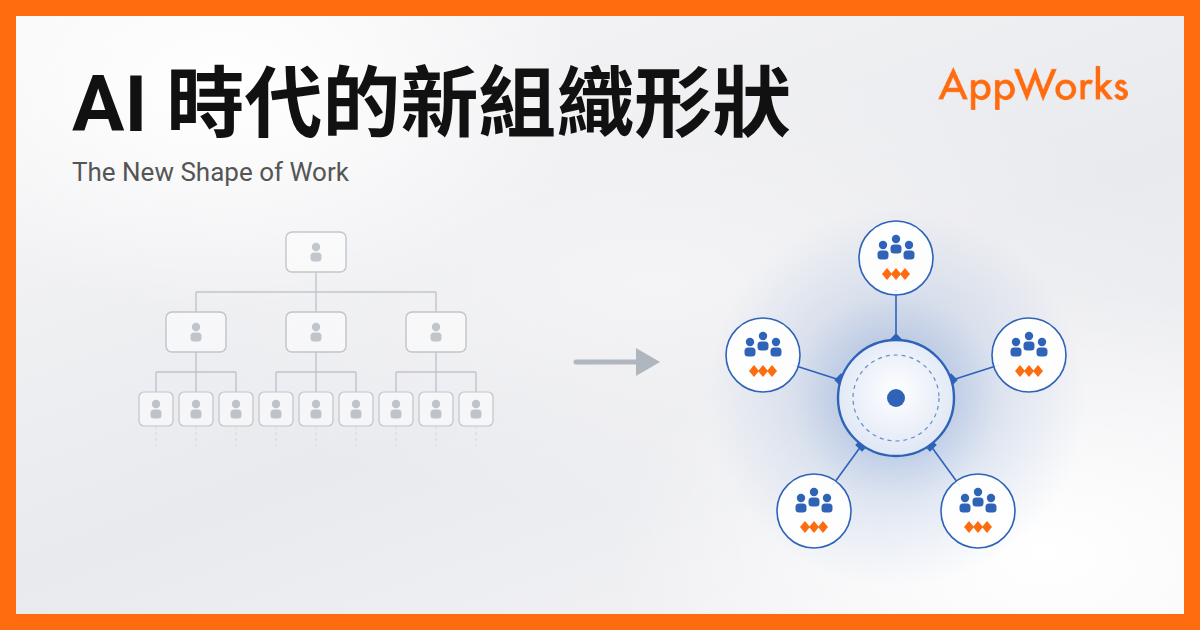
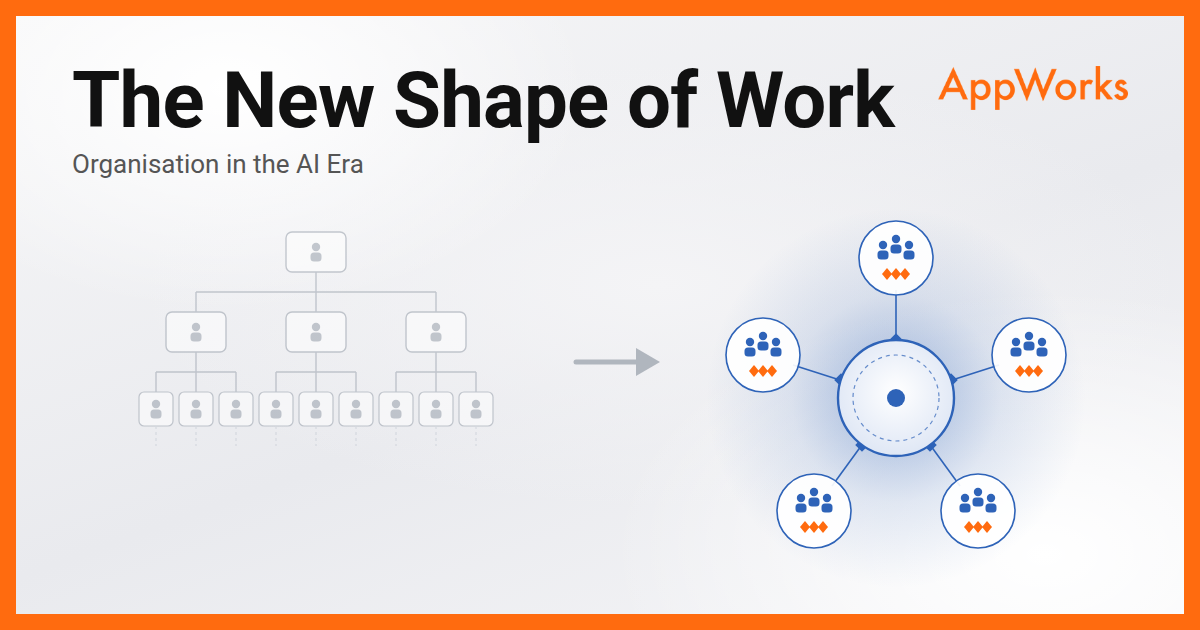
    Let’s lay out the full hypothesis first. We believe the organisation of the AI era may look like this: at the centre, a shared intelligent machine that takes on integration and execution; around it, a ring of small, self-sufficient outcome squads — two to five people plus a fleet of agents — each owning one outcome end to end; and expertise is no longer the name of a department; it is the repertoire a person brings to the work — a craft honed inside a guild.

    The history of management is full of organisational experiments, and organisation is one of the reasons American firms pulled ahead. Ethan Mollick, the Wharton professor who has written most persistently about organisational change in the AI era, points to an often-forgotten estimate: 20% to 40% of the extra competitive advantage American companies enjoyed in the twentieth century came from better management — it was an era willing to run experiments on the organisation itself. Yet he also laments that most companies later gave up experimenting, outsourcing “how to run a company” to consultants and SaaS vendors (see the interview published by Insight Partners).

    Indeed, looking back at management history, we have been through several major rounds of organisational experiment: the U-form of a century ago, grouped by function; then the M-form that grew up in the 1920s, grouped by division — both names in fact had to wait until 1975 for Oliver Williamson to supply them, the shapes having been alive for half a century before the theory caught up; then the amoeba system Kazuo Inamori invented at Kyocera in the 1960s, which split the company into dozens of small units each accountable for its own profit and loss; and on to Spotify’s squad model of the 2010s, copied the world over and yet never really made to live even at Spotify itself (see former Spotify PM Jeremiah Lee’s Failed #SquadGoals). Now AI has reopened the laboratory of the organisation. We would also like to give the new shape a name of its own, and in this article we tentatively call it the S-form: squad-form, an organisation grouped by outcome.


    Four key details of the new shape

    1. Group by outcome, not by function.

    Software has already taken this step. Since 2001, the engineering squad has put front-end, back-end, QA, design, PM, and ops on one team, accountable for specific outcomes instead of each returning to a functional department to wait in line.

    For other kinds of knowledge work, one of the reasons departments exist is that a complete piece of output is beyond one person, or a few: a single campaign takes a whole group to see through, and no one outcome can support a full-time designer, lawyer or analyst of its own. So the only option was to gather people of the same function together and let each person’s time be shared out across different outcomes — at the price of queueing, and of negotiating the order of the queue. Once that output can be supplied by a machine on demand, an outcome no longer needs a full group assembled around it, nor does it need to share a person with anyone else, and the boundaries can be redrawn — drawn between one outcome and the next.

    So what the new shape does is extend the same equation across the whole company: one team, one outcome, and inside it the best combination that could be assembled for that outcome — product, marketing, sales, perhaps — each person bringing their own profession, but sitting at the same table. The difference is this: what a squad used to deliver was one specific piece of the whole; in the age of AI, a single team can aim straight at a company-level outcome.

    1. Squads get smaller.

    The software industry’s long-standing reference point has been Amazon’s two-pizza team: small enough to be fed by two pizzas, so under ten people. But the pizzas were never the point. What Bezos actually wanted was a team that owned one thing outright, and Amazon later changed the wording to single-threaded ownership. Once most of the execution sinks into the machine, what is left for people is judgement and accountability — and that takes fewer of them still.

    The direction the big technology firms are moving in is already clear: this year Instagram replaced what used to be a thirteen-person specialist line-up with four to six generalist engineers, one product person, plus one specialist relevant to the problem at hand — a pod of roughly six or seven people (from Head of IG Adam Mosseri’s July interview on Lenny’s Podcast). What is worth noting is that the headcount is nearly halved and the composition has changed too: specialists give way to generalists, and the boundaries between functions begin to dissolve into one another.

    1. Departments don’t die; they get unbundled.

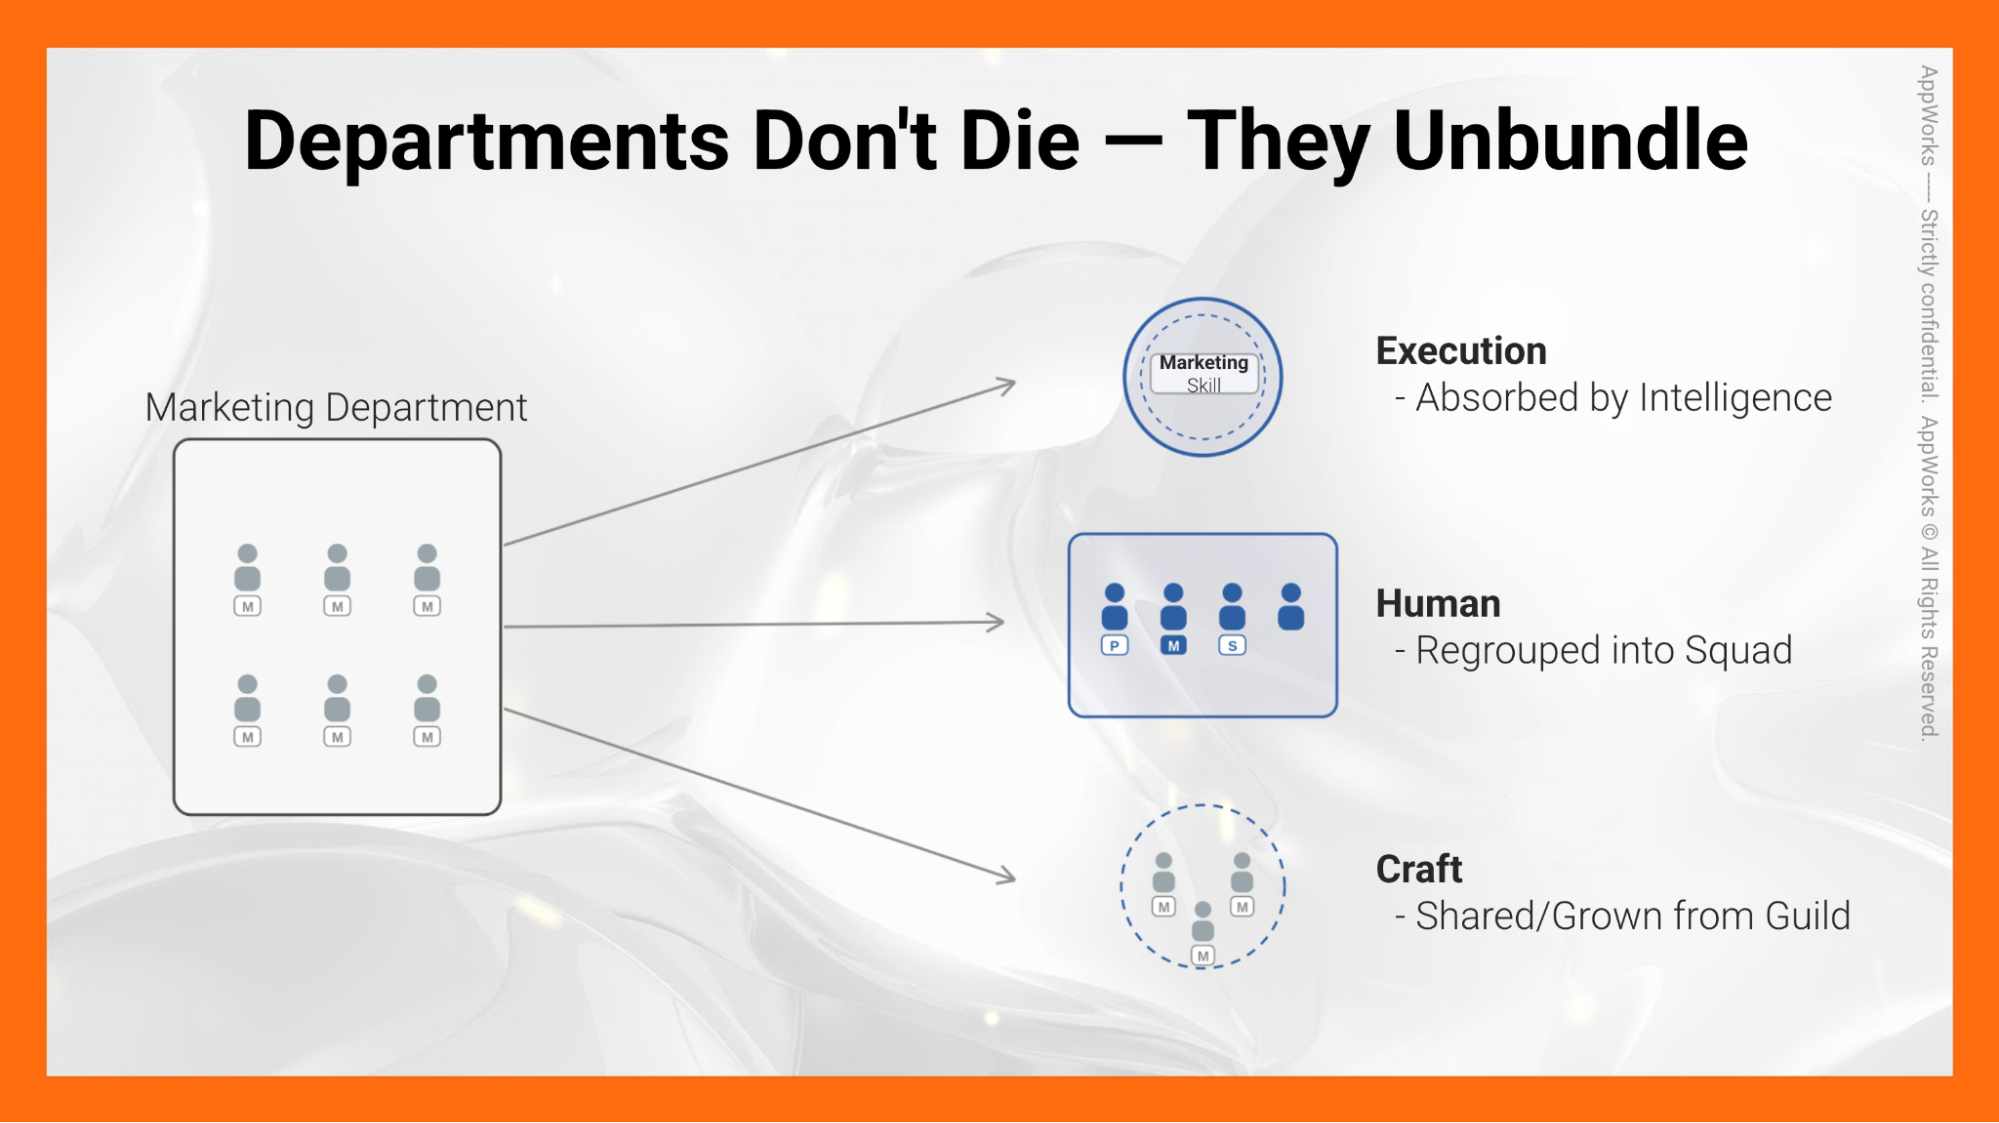
    This is the most misunderstood step. A department is really a bundle of three things: the capacity to execute, the power to decide whose work a person’s time goes to first, and a home for the craft. The new shape unbundles them, and each goes somewhere different.

    Capacity sinks into the machine. The scheduling power simply disappears — once an outcome no longer has to share a person with anyone else, there is nothing left to put in order, and people sit directly in the outcome team. And the community of craft becomes a guild: practitioners of the same discipline still gather to trade experience, hone standards and bring on newcomers, only now the guild sits off the delivery path — it signs nothing off, and nobody queues for it. A profession, then, is no longer where a person belongs, but the practice they bring into the team: visible in the work, yet not the whole determinant of what they can do.

    1. Underneath is a shared machine, and the people who tend it are a squad of their own.

    Management theory named this idea a long time ago: organisational knowledge. In the 1990s, Ikujiro Nonaka described how tacit knowledge becomes explicit, and industry duly built a generation of knowledge-management systems — most of which ended up as graveyards, because a knowledge base only stores, it doesn’t do the work, so nobody had any reason to open it. Thirty years on, a company’s real judgement and real way of doing things still sits, for the most part, in the heads of a handful of people (FunNow’s experiment, later on, comes back to this).

    The machine underneath the new shape is the first time that old idea can actually run. It doesn’t merely remember how the company does things; it is where the company does them: integrations, campaigns, quotes and work orders all run inside it. So every run teaches it a little more — though let’s be honest here, the machine does not get cleverer by itself. Someone is tuning context, managing agents and watching yield every day, extracting what happened and feeding it back in. That team is the fab process engineer of the new organisation, and their outcome is the machine itself getting better by the day.

    Don’t underestimate this team: encoding a company’s judgement, its knacks and its way of working into the machine, piece by piece, may be the single largest economic undertaking of the coming decade (a point also made by George Sivulka in an a16z article) — and every company has to do it for itself. Nobody can do it for you on contract. 

    This is also where the new shape’s biggest risk is buried: a shared machine is a shared dependency. If every team has to queue for this one team to supply the capability it needs, the queue you just dismantled grows straight back, merely in a different place. So the design principle for this machine is not to build bespoke features for each team, but to turn capabilities into interfaces the teams can plug into themselves — otherwise it becomes the new internal agency, which is precisely the thing the new shape set out to dismantle.


    Field notes from the pioneering founders

    FunNow: how a growth-stage GSEA startup is rebuilding its organisation, squad by squad

    The most complete experiment notes from our interviews came from FunNow, a booking platform for hospitality, dining and lifestyle services across Taiwan and Greater Southeast Asia (GSEA), led by group founder and CEO TK Chen, who is a member of the Paramount CEO Club in Taiwan and a regular mentor in the AppWorks community. (Note: Paramount CEO Club is a community for CEOs from companies at growth stage or beyond. It was established by AppWorks in 2012 and has two chapters, in Taiwan and Indonesia.)

    FunNow’s org chart today has no CMO and few management layers; increasingly, squads report straight to the CEO. Squads are organised by company-level outcome rather than function: one squad for conversion, one for membership and repeat purchase, one for booking flow, with payments and notifications bundled into a “core” squad. Every squad is designed to last at least twelve months, with two or three adjacent goals bundled so a team doesn’t disband when one is done. After all, familiar people and the rapport between them are still a critical part of organisational efficiency.

    The motive is not fashion. FunNow is ten years old; efficiency and profitability are pressing concerns; and functional departments carry a structural friction: one outcome split across departments, priorities that can’t be reconciled, disputes landing on the CEO’s desk. When one squad owns one outcome, “you no longer have to negotiate other departments’ schedules every day.”

    The human-to-agent ratio is set by how critical the interface is: “Membership features are simple, so the developer can be an agent. Payments and booking touch the core, so it may take two human developers and three agent developers.” The 2025 Annual Work Trend Index from Microsoft calls this the human-agent ratio — it has an optimum, not a maximum. Roles are allowed to blur (“once the UI/UX is drawn, why not add an agent and push the code yourself?”), but every squad keeps a permanent DRI (directly responsible individual). 

    Interestingly, Dorsey’s experiment has DRIs too, but there they are temporary roles that rotate with the task and follow the problem; what he really wants to remove is the permanent management layer. On this point, we agree with TK: that step goes too far. TK’s version keeps the DRI as a permanent person — “whoever answers for the failure gets the final say.” After all, it is people, not agents, who can be jailed or sued.

    The rollout is incremental: “Each time a new independent mission is confirmed, I pull out an outcome squad led by a DRI, and the old organisation gets remade bit by bit.” Marketing is furthest along, with agents running the chain from signal to execution while people judge and approve. From ad ideation to going live on Meta and Google used to take two weeks; it now takes under a day, and local marketing per country went from three people to two. “How short can you make the chain from market signal to executed response? A week, a day, an hour — that is what competitiveness means in the AI era.” Adoption is an armoury, not a mobilisation order: “AI is a weapon. Let everyone use it. If it works, double down.” Within months, users were modifying the agents themselves.

    The biggest bottleneck, he says, is institutional knowledge: the organisational World Model Dorsey describes “right now lives in the heads of individual managers and founders.” TK’s fix is to consolidate tools to two or three, then run weekly and monthly automated extraction so what happens becomes a company asset. The risk he names: when everyone is a builder, data permissions and deployment discipline will be the next governance problem.

    Staffinc: an Indonesian startup’s answer to uneven tech literacy

    The second set of notes comes from Indonesia. Founder Wisnu Nugrahadi is a member of the Paramount CEO Club in Indonesia. His startup, Staffinc, is an AI staffing company backed by AppWorks Fund. Wisnu began aggressively remaking the company after the shock of ChatGPT in 2023, and today it is a growth-stage startup with ten times the management efficiency of a traditional staffing agency (note: measured as the number of contract workers each HR staffer can manage).

    Wisnu is frank that the market conditions he faces are not comparable to a mature economy’s: the gap in tech literacy among employees is enormous. So he has run a great many experiments — first equipping everyone with AI, then building an in-house enterprise AI along the lines of a World Model with agents, and now a further step: give up on everyone becoming an AI builder, but make sure every team has a top-tier AI engineer.

    “It’s too expensive. When you give every employee AI, not every employee produces more, while the training and token costs are staggering.” When their local team’s fluency with the tools can’t keep up, don’t count on everyone becoming a high-performance AI user. So their latest approach is to embed one engineer in every sales squad (squads are organised by customer type), responsible for all the tools and systems that squad needs — in effect, an internal forward-deployed engineer (FDE).

    The biggest management innovations are (1) changing how engineers are evaluated: their performance is judged on the squad’s sales results, not by the engineering team; and (2) these deployed AI engineers still return to the engineers’ guild every week to swap the tools and lessons they have built, so that each squad’s learning becomes the whole company’s asset. 

    The same shape grows different transitional forms in markets at different levels of maturity — one more illustration that “shape follows what actually works.”


    Earlier-stage startups finding their way

    The Staffinc case shows that embedding AI into an organisation and getting outsized leverage from it is never a matter of the founder drawing a blueprint and following the script; it is a process of iteration and trial and error. Founders’ key concerns are broadly the same: lower cost, higher efficiency, new revenue. However, the path there has to be found by the founder leading the team, growing the new shape that best fits the company’s DNA. That is true for relatively well-resourced growth-stage companies, and all the more so for small startups running extremely lean.

    無毒農 (AW#5), a fruit-and-vegetable e-commerce company in Taiwan, learned this the hard way. Founder Enzo initially handed AI adoption to his CTO to lead, but months went by with no results. So Enzo rolled up his own sleeves: he started with n8n and the most repetitive work in customer service, then reshaped the engineering team’s makeup and working habits, and went on to build an internal company MCP (Model Context Protocol) server so that both AI tools and everyone on the team could pull the data they needed. The results: doubled customer service efficiency, sales up 30%, and product development capacity doubled outright.

    Tammy, founder of the blockchain team Numbers (AW#23), started by building an AI culture: every team member gets a US$20 monthly AI experimentation budget, the whole team demos their output weekly, and Tammy helps debug personally. Through six months of experimenting, she moved the people who couldn’t adapt to the AI culture out of the organisation. She then found that the cost of moving information between the existing SaaS systems was extremely high and AI couldn’t connect them effectively, so she cancelled all SaaS subscriptions and built the company an AI management system by hand, starting from the calendar. Each stage was built on the foundation of the one before, not a roadmap drawn at the outset.

    Farmio (AW#31), a Singapore-based AI solution for the food supply chain, was founded in the GenAI era and built AI-native from day one. What an AI-native food supply chain actually looks like was something founder Paco designed himself, starting from the smallest scenario: ordering via WhatsApp. He entered at the highest-frequency touchpoint in the entire supply chain and extended down the chain one link at a time. Two years on, 72 agents cover every workflow, ordering to delivery is almost fully automated, and the company has hit the milestone of US$1 million in GMV per employee.

    These three cases show the different paths smaller startups in the AppWorks community have taken, and each started its experiment at one clearly defined point: customer service, internal tools, ordering. Beyond that, the founder’s own resolve to change was critical to their success. The new shape of an organisation cannot be a job that gets outsourced — which brings us back to Professor Mollick’s lament: for decades, many companies outsourced “running the business” to consultants and system vendors, and the pioneers of this round of organisational experiments are taking it back into their own hands.


    The new shape gets you the ticket; the real arena is atomic capabilities and moats

    To pull the threads together: what we have been discussing is a new shape for the organisation. Over the past six months, founders have been busy chasing the rapid evolution of AI technology, and simultaneously innovating on organisational shape to keep pace. That is the common starting point of every experiment in the first half of this article. But once you have the new shape, there is one more layer to think through: a shape is something visible and copyable. When it goes from a few people’s experiment to every company’s standard equipment, what will actually decide who wins?

    In the short term, the gap between companies will come from who compounds learning first: the same headcount, several times the output. That gap is already measurable. Using the same frontier models, companies that hand out tools without touching the organisation see engineering productivity gains of roughly 20% to 40% (Theory Ventures’ data), and some rigorous controlled experiments have even measured negative values; companies that rebuild AI into their workflows see 2.5x to 3x (interview with Anthropic engineers); and in Taiwan we have already seen leading software companies reach at least 10x production speed. Everyone has the same models; the variable that makes a tenfold difference is not the model but how the organisation is built around it.

    But over a longer horizon, a shape is something visible and copyable. Once every company has grown into the new shape, the value of leading on execution and efficiency will eventually be competed away, and quickly. At that point, the decisive factors come back to two things. First, atomic capabilities — for FunNow that might be price discovery and the entertainment options it curates; for Staffinc, guaranteeing the quality and quantity of its contract workforce — and these atomic capabilities will be sorted into winners and losers ever faster. Second, moats that AI cannot take away: the licences, distribution, brand, and data loops a company needs in order to strengthen or defend that atomic capability.

    But don’t read “will be competed away” as “doesn’t matter.” A company that fails to grow the new shape will very likely not even get a seat at the table. The new shape is not a trophy; it is the ticket in — and the fastest way to accumulate those scarce assets.

    So before you start rebuilding, it is worth asking yourself two questions: is your atomic capability strong enough to be worth amplifying with the new shape? And what is your moat?


    Closing thoughts: an invitation from the frontier

    In closing, we want to be honest about how this revolution feels right now: it is not entirely romantic. In a 2026 survey of nearly 6,000 tech workers, only about one in five feared being replaced by AI, while more than half feared “doing more work for the same pay.” For founders, this is not employee anxiety; it is a diagnosis. Hand out tools without changing the shape of the organisation, and the capacity AI creates ends up backfilled as more meetings and longer hours. Being filled up is not a side effect of AI; it is a symptom of the old shape.

    Over a longer horizon, people’s place in the organisation tends to move toward the most valuable thing they do: judgement. After the spreadsheet arrived in the 1980s, the US lost about 400,000 bookkeeping and accounting clerks but gained about 600,000 accountants, and FP&A emerged as an entirely new job category. So the real question was never “how many employees will AI replace?” It is: when the machine gives the hours back to people, where should those people be redeployed? 

    No one can answer this for you, and it is the most important decision a founder faces right now. Every pioneer’s opening move was small, so if we had to give one concrete piece of advice: pick the outcome that hurts you most and that you can describe most clearly, take it out of the departments’ hands, and give it to a squad of two to five people plus a fleet of agents, with independent metrics and at least twelve months. You will quickly find out what your company’s new shape looks like.

    Finally, my recent favourite book is Benjamín Labatut’s When We Cease to Understand the World. Every time one of its scientists ceases to understand the world, a new theory is about to be born. For the first time in 25 years, the org chart is on the verge of being redrawn: the uncertainty, the fumbling, are proof that we are standing at the frontier. Over the past hundred years, each generation of operators experimented on their own companies, and each left behind a name: the U-form, the M-form, the amoeba. Whether the S-form becomes the next letter is up to this generation of founders and their experiments.

    At the start of the AI era, it is our honour to explore this new frontier with you.

    AI 時代的新組織形狀 The New Shape of Work

    with contribution from Natasha Chou, Alumni Relations Manager at AppWorks


    身處一個龐大的創業者社群,最寶貴的事,是能親眼見證創業者們每天的快速迭代。尤其今年初 OpenClaw 龍蝦登場以來,創業者們像是拿到了全新的火把,正在探勘 AI 能帶組織走進多少過去走不進的隧道。

    自 2025 年 4 月起,AppWorks 每個月在台北辦公室舉辦 AI Founder Circle,同步也在我們有 98 家活躍校友新創的新加坡雙月舉辦。十多場活動下來,議題一路演進:從怎麼用龍蝦,到怎麼打造自己的 AI Agent;從怎麼讓員工順利導入 AI,到動手打造 AI 員工、架起整套 Agent harness 平台……到現在,我們來到一個新的邊境:過去的組織形狀,好像不再適用了。

    組織形狀的升級優化,一直是新創成長路上必經的課題。幾乎所有公司的起點,都是一支只有數人的游擊隊,每天完全對焦、全力以赴;然後在成長的路上,似乎就得跟著大公司前輩們的足跡,走向部門化、事業部化,並開始感受到成長痛,尤其通常在一、兩百人這個區間,會經歷組織擴大了、生產力卻不見得等比增加的痛。

    要成就大的生意,必得有眾人加入艦隊;但人一多,管理就難,畢竟人類傳遞資訊的頻寬有限。AI 似乎正要化解這個千年的管理之痛:它傳遞資訊,比人更大量、更迅速、也更能超越不同人經手帶來的落差。前衛的創業者與企業家已經開始實驗:Jack Dorsey 三月提出完全扁平化的假說 (參考他與 Sequoia Managing Partner Roelof Botha 合寫的 From Hierarchy to Intelligence);Cloudflare CEO Matthew Prince 五月投書華爾街日報,解釋為何在營收高速成長、現金流健康的時刻裁員換血 (原文 How I Choose Which Cloudflare Employees to Replace with AI);我們 AppWorks 的董事長暨合夥人 Jamie,也與台灣大哥大資訊長蔡祈岩於七月份出版《逆分工》探討 AI 時代的生產力革命。

    在亞洲,許多創業者正同步進行這樣的實驗。透過他們第一手的經歷與迭代,我們有幸近身觀察。今天藉由這篇文章提出一個關於 AI 時代組織形狀的假說,想跟拿著火把的創業者們,一起窺見未來的樣貌;而文章的末尾,我們會說明,為什麼新形狀是重要的入場券,而不是終局。我們同時邀請了幾位不同階段與規模的創辦人,分享他們正在做的實驗與成果,所以這篇文章不只是 AppWorks 提出的一個理論,更是來自 AppWorks 創業者社群無私的分享。


    每一次技術革命,都會重塑我們組織的方式

    每一次技術革命,都會重塑我們組織的方式,而這件事至少發生過兩次了。

    第一次在紡織廠。18 世紀工業革命前,織布機只是工具,手藝長在織工身上,一人一機,產量的上限就是人手。動力織布機出現之後,機器把手藝吸收了進去,人站到機器的旁邊,人來看顧機器執行手藝。一個人看管一整排機器,工作從動手織布,變成設定標準、抓出例外。2026 年的今天走進台積電的晶圓廠,你看到的仍然是這個形狀:最先進的製程工程師,不是任何一片晶圓的工匠,是機器良率的看顧者。

    第二次,輪到軟體業自己。從大型主機、個人電腦到雲端,工程師的工具有個特別之處:寫得成規則的事,工具就能替你做;而它最先接管的,是「證明上一個人沒做錯」。早期的 waterfall 按工序分組,分析、設計、寫碼、測試,四個部門輪流交接,文件就是縫線;那份文件真正的功能,是把信任從上一棒交到下一棒。當版本控制、自動測試、持續整合把驗證變成機器的工作,雲端又讓上線從一次定生死變成隨時可回滾,交接的文件就沒有東西要證明了。崩掉的不是人力工時,是犯錯與協調的成本;成本一變,形狀跟著重組。大約 2001 年起,敏捷開發 (agile) 把跨職能小隊變成軟體業的主流:一個小隊裡有產品、工程、設計,一起對「提升首頁轉換率」這種專項成果負責。(Spotify 後來把這種小隊叫做 squad。)

    形狀從來不跟思潮走,只跟真實的成效走。這也解釋了產業發展的往事:過去 25 年,agile 在網路服務的工程團隊以外幾乎沒有真正成功過,因為搬得走的只有儀式,搬不走的是底下那台機器。其他部門的系統只記錄工作,不做工作,更不會查工作:CRM 記錄客戶,但不去談客戶,也不會告訴你這通電話談壞了。少了那台機器,跨職能小隊交出來的成果沒有變好,只是換一種方式開會;於是儀式留著,形狀退回去。


    知識工作者的革新時代

    看看今天的公司:一個客戶成果,通常切給產品、行銷、業務、客服四個部門,各自對自己那一段負責,再開會對齊。而知識工作者的日常,大半是在系統之間搬資料:從 email 搬進 CRM、從報表搬進簡報。企業 IT 有個正式術語形容這件事,叫 swivel-chair integration 旋轉椅整合:這邊轉過來複製,那邊轉過去貼上。有了滿桌的系統與工具,知識工作者卻還在手搖織布機的時代。

    AI 對知識工作做的,正是動力織布機對紡織做的事:把手藝吸進機器裡。它先接管了搬運和串接,隨即連各部門的執行也吸了進去:行銷的投放、業務的報價、客服的工單等等,各種人力執行的工作,都變成機器裡隨叫隨到的能力,形同內勤工作的 API 化。

    這是知識工作者的工業革命時代,白領第一次可以真正站到機器旁邊。下一個問題就是我們今天想要談的假說:站到旁邊的人,該怎麼重新組織、重新編隊?


    我們的假說:一個新形狀 The New Shape of Work

    先把完整的假說畫出來。我們認為 AI 時代的組織,可能會長這樣:中央是一台共用的智能機器,把串接與執行扛走;機器周圍,環繞著一個個小而完整的成果小隊,每隊二到五個人加一支 agent 編隊,完整擁有一個成果;專業不再是部門的名字,是人做事的手路、行會裡磨出來的手藝。

    管理學歷史上有許多組織實驗,而組織,正是美國企業得以領先的要素之一。華頓商學院副教授 Ethan Mollick 是近年談 AI 時代組織變革談得最持續的人之一,他提醒過一個常被遺忘的估算:二十世紀美國企業多出來的競爭優勢,有 20% 到 40% 來自更好的管理,那是一個願意拿組織做實驗的年代;但他也感嘆,後來多數公司放棄了實驗,把「怎麼經營公司」外包給顧問與 SaaS 廠商 (見 Insight Partners 刊出的訪談)。

    的確,回頭看管理史,我們經歷過幾輪大的組織實驗:一百年前按職能分組的 U-form;緊跟著在 1920 年代長出來的 M-form,按事業部分組——這兩個名字其實都要等到 1975 年才由 Oliver Williamson 補上,形狀先活了半世紀,理論才追上;1963 年稻盛和夫在京瓷發明的阿米巴,把公司切成數千個各自算損益的小單位;再到 2010 年代 Spotify 那套被全世界抄走、卻連 Spotify 自己都沒能真正活下來的 squad 模型 (見前 Spotify PM Jeremiah Lee 的 Failed #SquadGoals)。如今,AI 把組織的實驗室重新打開。我們也試圖給新形狀一個名字,暫且叫它 S-form:squad-form,按成果分組的組織。


    新形狀的四個關鍵細節

    一、以成果分組,不再按專業分工。 

    這一步軟體業早就走過:2001 年以來的工程 squad,把前端、後端、QA、設計、PM、維運湊在一隊,對特定專項目標負責,而不是各自回到職能部門排隊。

    對於其他知識工作來說,部門的存在理由之一,是一個人、幾個人做不出一份完整的產出:一次投放要一整組人才跑得完,一個成果也養不起一名專職的設計、法務或分析師。所以只能把同職能的人集中起來,讓每個人的時間被不同的成果分著用,而代價是排隊,以及排隊順序怎麼談。當那份產出可以由機器隨叫隨到地補齊,一個成果不必再湊滿一組人,也不必再跟別人共用同一個人,邊界就得以重劃,劃在成果與成果之間。

    所以新形狀做的事,是把同一個等式擴到整家公司:一個小隊,一個成果,裡面是為了這個成果湊齊的最適組合,可能有產品、行銷、業務,每個人帶著自己的專業,但坐在同一張桌子。差別在於:過去 squad 交付的是一個特定專項,在 AI 的時代,一個小隊可以直接瞄準公司級的成果。

    二、小隊更小。 

    軟體業長年的參考值是 Amazon 的 two-pizza team:兩張披薩餵得飽,十人以內。但披薩從來不是重點,Bezos 真正要的是一支隊伍完整擁有一件事,後來 Amazon 也把說法改成 single-threaded ownership。當執行大部分沉進機器,人剩下的工作是判斷和問責,需要的人就更少了。

    科技大廠的移動方向已經很清楚:Instagram 今年把過去十三人的專才編制,換成四到六位通才工程師、一位 product staff,再加一位切題的專才,整支 pod 大約六到七人 (來自 Head of IG Adam Mosseri 在七月份 Lenny’s Podcast 的訪談)。值得注意的是,人數幾乎腰斬,組成也改變了:專才換成通才,功能的邊界開始互相溶解。

    三、部門不死,是拆包。

    這是最常被誤解的一步。部門其實是三個東西的捆綁:執行的產能、決定一個人的時間先給誰的調度權、手藝的家。新形狀把它拆開,各有去處。

    產能沉入機器;調度權消失了——當一個成果不必再跟別人共用同一個人,就沒有東西需要被排序,人直接坐進成果小隊;而手藝的社群變成行會 (guild):同行仍然聚在一起交換經驗、磨標準、養成新人,只是行會不在交付的路徑上,不簽核、不排隊。專業於是不再是一個人的歸屬,而是他帶進小隊的手路:看得出來,但不完全決定他能做什麼。

    四、底下是一台共用的機器,而顧機器的人,自己就是一個小隊。 

    管理學很早就有這個概念的名字:組織知識。野中郁次郎在 1990 年代講內隱知識如何變成外顯知識,企業界跟著蓋了一輪知識管理系統,結果多半成為墳場——因為知識庫只存,不做事,沒有人有理由打開它。三十年過去,一家公司真正的判斷與做事方法,多半還是留在少數幾個人的腦子裡 (稍後 FunNow 的實驗會回到這一題)。

    新形狀底下這台機器,是這個舊概念第一次能執行。它不只記得公司怎麼做事,它就是公司做事的地方:串接、投放、報價、工單都在裡面跑。所以每跑一次,它就多知道一點——但這裡要誠實,機器不會自己變聰明,是有人每天在調校 context、管理 agent、顧良率,把發生過的事萃取回來。這支小隊,就是新組織裡的晶圓廠製程工程師;他們的成果,是機器本身每天變得更好。

    別小看這支小隊:把一家公司的判斷、眉角、做事的方式一點一點編碼進機器,可能是未來十年最大的一項經濟工程,而且每家公司都得自己做一次,沒有人能替你代工。

    這裡也埋著新形狀最大的風險:一台共用的機器,就是一個共用的依賴。如果每支小隊要的能力都得排隊等這支小隊補上,剛拆掉的排隊就會原地長回來,只是換了位置。所以這台機器的設計原則,不是替每支小隊客製功能,而是把能力做成他們自己接得上去的介面——否則它就變成新的內部乙方,而那正是新形狀要拆掉的東西。


    先行者的實驗筆記

    FunNow:GSEA 成長期新創如何漸進重組整個組織

    這不是紙上理論。過去幾個月的訪談裡,最完整的一份實驗筆記,來自 FunNow。FunNow 是橫跨大東南亞 (Greater Southeast Asia, GSEA) 的旅宿、餐飲等生活服務即時預訂平台;集團創辦人暨執行長陳庭寬 (TK Chen) 是 AppWorks 成立的 Paramount CEO Club (峰會) 會員,也長期在 AppWorks 社群擔任創業導師。

    這家橫跨多國的即時預訂平台,今天的組織圖上沒有 CMO,也沒有多階管理層,越來越多是直屬 CEO 的小隊;小隊有清楚獨立指標,為自己負責。他們正在進行一場漸進式的實驗,把切隊的軸線從職能改成公司級的成果:轉換率一隊、會員與回購一隊、訂位流程一隊,支付和通知這種相鄰的基礎設施,則綑成一個 core 小隊。

    純粹按成果切隊有一個天然的問題:成果有壽命,目標做完,隊伍就地解散,好不容易磨出來的默契也跟著散掉。TK 的解法很務實:每支小隊一次綑兩三個相鄰目標,刻意設計成至少存活十二個月。熟悉的人與默契,仍然是組織效率中極為重要的一環。

    人和 agent 的配比,按介面的關鍵程度來調。「舉例來說,會員功能比較簡單,RD 可以是 agent;但支付、訂位碰到核心,可能要兩個真人 RD 跟三個 agent RD。」微軟在 2025 年的 Work Trend Index 裡,也把這件事命名為新的管理指標 human-agent ratio:它存在的是最適值,不是最大值。

    角色的邊界,則是刻意讓它溶解:「被 AI 賦能後,BA 也能畫 UIUX?UIUX 畫好,為什麼不能自己加個 agent 把 code 丟上去?」但溶解不等於沒有秩序,每隊有一位 DRI,對成果負最終責任。有趣的是,Dorsey 的實驗裡其實也有 DRI,只是那是一個隨著任務時程輪替、跟著問題走的臨時角色;他真正想拆掉的,是常設的管理層。聊到這裡,我們和 TK 的共識是:這一步走得太理想。TK 的版本把 DRI 留成常設的人,「誰最後 fail 誰說了算」,畢竟究責這題,機器接不了,輪替的人也接不牢,最終能被關、能被告的,是人不是 agent。連 Dorsey 自己都在文章裡承認:這場轉型會很艱難,「有些部分可能要先壞掉,才會開始運作」。

    問 TK 為什麼此刻動手,理由並不浪漫。FunNow 創立已滿十年,是進入成長期的公司,提升效率與獲利,是迫切的營運議題,而不是趕潮流的實驗。而傳統按職能劃分的部門,始終存在一種結構性的內耗:同一個成果,被拆給不同部門分擔。B 部門同時接下三個 A 部門的需求,優先順序談不攏,最後吵到執行長桌上仲裁。這種內部的甲方乙方關係,正是新形狀要拆除的東西。當一支小隊完整擁有一個成果,「不再需要天天為其他部門排程。」

    推進的方法論也值得分享:「我不是一次把它打散,每確定一個新的獨立任務,就把一個 DRI 帶領的成果小隊拉出來,舊的組織就會慢慢被改造。」目前走得最前面的是行銷:TK 把這個職能拆成左腦 (內外部數據)、右腦 (創意生成) 和雙手 (投放後台),目標是讓 agent 從訊號到執行跑完全程,人做判斷與審批,流程完全改造。現在的成績:從廣告發想、製作並刊登到 Meta/Google 後台,原本需要兩週,現在能降到一天內完成;各國在地行銷從三人減到兩人。「能把市場訊號到反應執行的鏈縮到多短?一週、一天、一小時,才是 AI 時代公司的競爭力。」而推廣的心法是廣泛提供武器庫:「AI 就是武器,讓所有人用,打打看這武器好不好用。好用就加碼,再配備,再打。」兩三個月後,使用的人開始自己動手改 agent。

    他點名的最大瓶頸,是知識的沉澱:「Jack Dorsey 的實驗中提到組織版的 World Model,也就是透過各種資訊數據沉澱成公司對內與對外的理解,其實現在都存在每個管理者、或者 founder 的心裡面。」決策散落在 Jira 的附件、GitHub、Figma 連結和 Metabase 之間。TK 則是下兩帖藥:把工具收斂 (從每個人自己嘗試,六個月內已經收斂成兩三種主流),再靠每週、每月的自動萃取,把發生過的事實際變成公司的資產。風險他也不諱言:當每個人都是 builder,資料權限與上線紀律就是下一個治理課題。

    Staffinc:印尼新創面對人才科技素質不一的組織解法

    另一份筆記來自印尼。Staffinc 創辦人 Wisnu Nugrahadi 是 AppWorks 成立的 Indonesia Paramount CEO Club 的會員,Staffinc 本身也是 AppWorks Funds 所投資的 AI 人力派遣公司。他從 2023 年被 ChatGPT 衝擊後就積極改造公司,直到今天已經成為一個相比傳統人力派遣公司有十倍管理效率 (編按:每人力資源 HR 能管理的派遣員工數) 的成長期新創。

    Wisnu 坦承他們所面對的市場條件跟成熟經濟體無法比,員工的科技素質落差極大。也因此他做了非常多的實驗,先從人人配置 AI,到內部建置類似 World Model 與智能層的概念做出企業 AI,到現在有了更進一步的做法:放棄人人都成為 AI builder 的期待,但是確保每個團隊中都有超強的 AI 工程師。

    「太貴了,給每個員工用 AI 的結果是:並非每個員工都可以做出更高的產出,而培訓與 token 的費用卻非常驚人。」當團隊成員對工具的熟練度跟不上的時候,就不要抱持著人人都變成高效 AI 使用者的期待。所以他們最新的做法,是在每個按客戶類型分的業務小隊裡,配備一位工程師,負責這個小隊需要的所有工具與系統,也就是內部 FDE (forward-deployed engineer)。

    管理上最大的創新則是 (1) 把工程師的考績做調整,考績是看小隊的銷售成果,不是回到工程團隊;(2) 這些部署在外的 AI 工程師依然每週會回到工程師的行會,交換彼此做出來的工具與心得,讓一個個小隊的學習,變成整家公司的資產。

    同一個形狀,在不同成熟度的市場,長出了不同的過渡型態,這正是「形狀跟著成效走」的另一個案例。

    小型新創的摸索之路

    從 Staffinc 的案例可以看到,把 AI 嵌進組織、槓桿出更大的效益,從來不是創辦人畫好藍圖,照圖施工,而是一段迭代試錯的過程。創業者的目的地大致相同 (降本、增效、創造新收益),但其間途徑,得由創辦人帶領團隊自己摸索,長出最符合公司 DNA 的新形狀,資源相對充裕的成長期公司如此,人手極度緊繃的小型新創更不例外。

    無毒農 (AW#5) 在台灣經營蔬果電商,創辦人 Enzo 就在這件事上吃過苦頭。他一開始把 AI 導入交給 CTO 帶頭,過了幾個月卻不見成效,後來 Enzo 自己捲起袖子,從 n8n 開始,先解決重複性最高的客服,接著調整工程團隊的體質和工作習慣,並開始自建公司內部 MCP (Model Context Protocol,讓 AI 能直接調用公司資料的介面),讓夥伴都能調度需要的資料。結果是客服效率倍數提升、同期業績增加三成、產品開發產能直接翻倍。

    區塊鏈團隊 Numbers (AW#23) 的創辦人 Tammy 則從營造 AI 文化開始:給每個夥伴每月 20 美金的 AI 實驗基金,每週全員 demo 產出,Tammy 親自幫忙 debug 除錯。半年實驗下來,她將不適應 AI 文化的夥伴調離組織。之後發現原有 SaaS 系統之間資訊轉換成本極高、AI 無法有效串接,索性撤換所有 SaaS 訂閱,親手從 calendar 開始,為公司建起一套 AI 管理系統。每個階段都建築在前面的地基之上,不是一開始就畫好的路線圖。

    來自新加坡做食品供應鏈的 Farmio (AW#31) 是在 GenAI 時代才創立的公司,從第一天就以 AI-native 來打造。而 AI-native 食品供應鏈究竟長怎樣,也是創辦人 Paco 從一個最小的場景開始設計:WhatsApp 下單。從整條供應鏈最高頻的接觸點切入,一個環節一個環節往後延伸,兩年下來走到完整的 72 個 agent 覆蓋各個工作流程、從下單到配送幾乎全自動,達成員工人均 100 萬美元 GMV 銷售金額的里程碑。

    這三個案例是 AppWorks 社群內小型新創的不同摸索,都是從某個最明確的單點開始實驗:客服、內部工具、下單等等。除此之外,創辦人自己對於革新的決心,也是他們得以實驗成功的重要關鍵。組織的新形狀,不可能是一個能被委外的工作,這也回應前面提及 Wharton 教授 Mollick 的感嘆:過去幾十年,許多公司把「經營」外包給顧問與系統商;而這一輪組織實驗的先行者們,正把這件事,拿回自己手上。


    新形狀決定你的入場券,真正的競技場在原子級的能力與護城河

    走到這裡,把文章的重點收攏一下:我們談的是組織的新形狀。這半年,創業者們忙著追趕 AI 的日新月異,同時在快速實驗重新發明組織的機會,這是文章前半所有真實案例的共同起點。但拿到新形狀之後,還得再多想一層:形狀是看得見、學得走的東西。當它從少數人的實驗,變成每一家公司的標配,真正決定勝負的,會是什麼?

    短期內,公司之間的差距,會來自誰先讓學習複利:同樣的人數,做出數倍的成果。這個差距已經量得出來:用同樣的前沿模型,只發工具、不動組織的公司,工程生產力增益大約兩到四成 (Theory Ventures 統計),甚至有嚴謹的對照實驗測出負值;把 AI 重建進工作流的公司,是 2.5 到 3 倍 (Anthropic 工程師訪談);在台灣我們也看到領先的軟體公司已經出現至少 10 倍產出速度的案例。模型人人相同,差十倍的變數,是組織的形狀。

    但把時間拉長,形狀是看得見、學得走的東西;當每一家公司都長成新形狀,靠執行和效率領先的價值,最終還是會被競爭迅速稀釋。屆時,決勝點會回到兩件事:一是原子級的能力,比如對 FunNow 來說可能是價格發現與娛樂提供,對 Staffinc 則是派遣人力的質與量的保證,這些原子級的能力會更快地被分出優劣;二是 AI 帶不走的護城河,為了把原子級的能力提升或防禦,新創需要什麼樣的護城河,比如執照、通路、品牌、資料的迴路等等。

    但別把「會稀釋」讀成「不重要」。沒有長出新形狀的公司,接下來很可能連牌桌都上不去。新形狀不是獎盃,是入場券,而且是你累積那些稀缺資產,最快的方式。

    所以在動手重組之前,值得先問自己兩個問題:你的原子級能力,夠強到足以用新形狀放大嗎?你的護城河,又是什麼?


    結語:邊境寄來的請帖

    寫在最後,想先誠實面對這場革命此刻的體感:它並不全然浪漫。2026 年一份近六千名科技工作者的調查裡,怕被 AI 取代的只有兩成,怕「同樣的薪水、做更多的事」的超過一半。這對創業者不是員工焦慮,而是一張診斷書:只發下工具、不動組織的形狀,AI 換來的產能,最後只會回填成更多的會議、更長的工時。被填滿不是 AI 的副作用,是舊形狀的症狀。

    拉長時間看,人的位置終究會往最珍貴的價值移動,那就是判斷。1980 年代試算表出現後,美國少了約四十萬名簿記與會計文員,卻多出約六十萬名會計師,FP&A 更成為全新的職業品類。所以真正的問題從來不是「AI 會取代多少員工」,而是:當機器把工時還給人類,人該被重新配置到哪裡?這一題沒有人能代答,也是創業者現在最重要的決定。而先行者的起手式都很小,如果要給一個具體建議:挑一個你最痛、也最說得清楚的成果,從部門手上拿出來,交給一支二到五人加一支 agent 編隊的小隊,給他們獨立的指標和至少十二個月。你會很快知道,你公司的新形狀長什麼樣子。

    近期讀到最喜歡的書,是 Benjamín Labatut 的《當我們不再理解世界》:書裡的科學家每一次「不再理解世界」,都是新理論誕生的前夜。今天組織圖也正在進入我們不再確定的狀態,而這正是我們站在邊境的證明,此刻我們講的「邊境」不是國界,而是已知與未知交界的那條線。過去一百年的 U-form、M-form、阿米巴,都是某一代經營者拿自己的公司做實驗留下的名字;而 S-form 會不會是下一個字母,就看這一代創業者的實驗。

    在 AI 時代的起點,很榮幸能跟各位一起探討這場暌違 25 年的全新邊境。

    Why We Invested: Samyak Jain, Founder of Fluid

    DeFi already has Aave. So the first question anyone may ask is why build another lending protocol.

    Yet if one digs deeper, they will realize capital fragmentation still creates a huge structural inefficiency in DeFi today. The same dollar of collateral that backs a loan on Aave cannot also be an LP position on Uniswap. Aave, Compound, and Uniswap each wall their liquidity off from one another, so capital sits in one silo doing one job. Therefore, the world does not need another lending protocol, but we can all benefit from solving this structural inefficiency. 

    That’s why the world needs Fluid: it collapses those walls. The same collateral that secures a loan can finally also provide trading liquidity at the same time, and it shows up the cleanest measure of capital efficiency, revenue per dollar of TVL, where Fluid runs about 0.43% in 26Q1, the highest of any lending protocol. 

    But the number is not why we invested. What we care more is the team who can break the constraint while others just live with that. 

    Samyak Jain: The math geek who rebuilt everything from first principles 

    Samyak and his older brother Sowmay grew up in Kota, India’s academic-pressure capital. Samyak watched The Social Network in ninth grade and decided he wanted to start a company. He was a math prodigy and a competitive chess player. Sowmay started trading Indian stocks in high school and wrote his own apps to track them, and Samyak joined in to write the code. That was their first project together, and it ran straight into the walls of traditional finance, where your age, a missing license, or a lack of capital can simply lock you out.

    On his first day of college, Samyak told his parents he would drop out the moment he found an idea worth it. The idea showed up fast. In August 2018 the brothers entered the ETHIndia hackathon, built a tool on top of MakerDAO, and won. The takeaway stuck with him: two college students could write code that managed millions of dollars, and no one could stop them. They were crypto-native from the start, with a MetaMask wallet before a bank account. In 2019 Pantera and Naval backed them with $2.4M, Samyak dropped out, and they went all in on Instadapp. It became DeFi’s leading middleware and peaked at around $12B in TVL.

    Then came the moment that decided everything. In 2022, when LUNA collapsed and stETH lost its peg, Instadapp’s Lite strategy came close to roughly $1B in liquidations, and the team scrambled through emergency loans to survive. Samyak’s own summary is that those three days taught him three years’ worth of risk lessons. The most important one was simple and uncomfortable: middleware sits on top of other people’s protocols, and you cannot fix a broken foundation from the top. Most founders sitting on a $12B protocol would have kept shipping features. Samyak did the opposite. He stopped iterating on Instadapp and spent close to a year and a half rebuilding lending from the ground up, around one question: what would a bank look like if you built it from zero on-chain?

    Early 2026 put both the founder and the architecture through two real tests. In March, an attacker exploited a partner protocol, Resolv, and pushed about $80M of unbacked tokens into Fluid. Two things saved it. Fluid’s automated risk limits capped how much damage that bad collateral could do before any human reacted. And within about half a day, the team had sized the loss, lined up interest-free emergency loans from partners like Cyberfund and Jupiter, and publicly guaranteed user funds, which stopped a panic before it could start.

    The second test was system-wide. In April, a hack at Kelp set off a bank run across DeFi: everyone rushed to pull ETH out of lending markets at once, Aave’s ETH was fully borrowed out, and the cost of borrowing ETH spiked everywhere. Within hours, Fluid shipped a tool (its aWETH Redemption Protocol) that let lenders who were stuck in Aave get their ETH out, and in the process reduced Fluid’s own exposure at the same time. Fluid came out of the crisis looking like the lender of last resort.

    Fluid could have simply waited for Resolv to resolve its own exploit. Instead the team acted first, taking measure after measure to make sure user assets were protected. That perseverance, and the instinct to put user funds ahead of everything else, is what impresses us most. This is the kind of founders we at AppWorks are proud to back: those that are willing to rebuild from zero. On top of that, across both crises, what stood out was the speed and capability with which the Fluid team handled them.

    Beyond the design: how Fluid grows

    We won’t rehearse the mechanics here. The design is genuinely clever, with three pieces doing the work (Smart Collateral, Smart Debt, and the liquidation engine), and Cyberfund has already written the clearest explanation of how they fit together in its two-part Demystifying Fluid series.

    What we like just as much as the design is the go-to-market. Fluid runs its own protocol and is still building its own community, but its biggest growth lever is distribution: it takes the same engine and plugs it into channels that already have millions of users, instead of trying to win every user directly.

    Jupiter is the clearest example. It is Solana’s largest trading aggregator, so Fluid provides the lending engine, Jupiter brings the users, and together they launched Jupiter Lend with the economics split roughly fifty-fifty. The deal closed fast because the founders already trusted each other. On BNB, Venus, the chain’s largest lending protocol, now runs on Fluid through Venus Flux. And institutional curators are starting to arrive: Bitwise runs an Ethena market on the Fluid-powered Jupiter Lend, the first institutional-grade curator on the system.

    It is worth being precise about where the moat comes from. The obvious part is lock-in: once Fluid is the lending engine underneath a partner like Jupiter or Venus, ripping it out is so costly that almost nobody does, and Fluid gets there without paying for users through token emissions, the most expensive game in DeFi. But the deeper moat is less glamorous. Running a lending book well is genuinely hard operational work. Every collateral type needs its risk parameters set and watched, liquidations have to stay ahead of fast-moving markets, and the whole book needs constant risk management. Most teams do not want to touch any of that, which is exactly why being the team that does it well, on everyone else’s behalf, is so hard to dislodge. It also just makes economic sense: powering a partner earns Fluid far more than launching yet another vanilla lending protocol on its own would, so the partnership pays off for both sides.

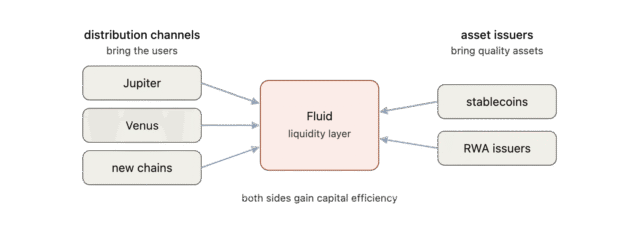
    That points to the bigger picture: Fluid is really a two-sided platform. On one side are the distribution channels we just described, the apps and chains that want a lending and trading engine without building one themselves. On the other side are the projects that need liquidity, like stablecoin and real-world-asset issuers, who can use Fluid’s pools to bootstrap a market far more cheaply than hiring a traditional market maker. When the reUSD stablecoin launched on Fluid, its TVL and trading volume jumped in a single day, and it has since spread across multiple chains. Fluid sits in the middle and makes both sides more capital-efficient than they could be on their own.

    The thing to understand is that these are not separate product lines. They are one architecture. Fluid is a single liquidity layer that any number of protocols can plug into, where the same capital is reused across spot, perps, FX, and credit. DEX, Perp, and FX are not different businesses, they are the same engine reaching into new asset classes, and each one adds revenue without needing fresh TVL. The north star is to rebuild banking from zero on-chain: to become the engine behind banks and neobanks, to bring real-world assets on-chain, and to make the kind of 95% LTV borrowing that today only billionaires with private bankers can get available to everyone.

    —

    We’re thrilled to back Samyak and the Fluid team as they rebuild banking from first principles on-chain, turning capital efficiency from a feature into the primitive the next financial system runs on.

    And if you are a founder building on-chain banking from first principles, we would love to talk.